A Bank of Canada Rate Hike Is Now a Coin Flip - Here Is What to Do Before October 28

Three weeks ago the safe assumption was that the Bank of Canada would sit still until spring, and that assumption is gone.  On Wednesday the U.S. Federal Reserve raised its rate by a quarter point, its first increase in more than three years, and by Thursday the market was pricing the Bank of Canada's October 28 decision as a coin flip, with the odds tilted slightly toward a hike (CP24 and The Canadian Press, September 18, 2026).  If you have a variable-rate mortgage or a fixed term that renews in the next year, here is what that shift means for your monthly numbers and what I would do about it now.

How we got from a hold to a coin flip in three weeks

On September 2 the Bank held its policy rate at 2.25 per cent for the seventh straight decision, with the market putting the odds of a hold at 94 per cent going in (Bank of Canada; LSEG data cited by The Canadian Press).  Two things changed the picture.  The first is inflation: Statistics Canada reported on September 14 that the consumer price index rose 3.0 per cent in August from a year earlier, the same pace as July, with rent up 2.8 per cent and Ontario leading that increase (Statistics Canada, The Daily, September 14, 2026).  Three per cent is the top of the Bank's comfort range.

The second is what the Bank itself said.  In the summary of its September deliberations, released on September 16, the governing council wrote that if higher energy prices spilled over into other parts of the CPI, "it could require a monetary policy response to prevent broad-based inflation from setting in" (Bank of Canada, Summary of Governing Council Deliberations, September 16, 2026).  Oil is above US$100 a barrel because of the conflict in the Middle East, and as RBC's Claire Fan put it, if one thing is driving the pricing of the October meeting, it is oil.  Most economists still expect the Bank to wait until early 2027, but a hold is no longer the only scenario worth planning for.

If you are on a variable rate

Prime sits at 4.45 per cent and the best five-year variable rates are around 3.40 per cent (Ratehub, September 18, 2026), and a quarter-point hike moves both by the same amount.  On a $700,000 mortgage with a 25-year amortization, a variable rate of 3.40 per cent costs about $3,458 a month and 3.65 per cent costs about $3,551, a difference of roughly $93 a month; a second quarter point would take it to about $3,644.  Those are real dollars, but not the kind of jump that upends a household budget, whatever the headlines suggest.  The larger risk sits with anyone on a variable mortgage with a fixed payment, where the payment stays the same while more of it goes to interest and the amortization quietly stretches.  If that is your mortgage, ask your lender for your trigger rate and how much principal you are actually paying down each month.

If your mortgage renews in the next twelve months

This is the group I am most concerned about, and it has little to do with October.  Many of the mortgages taken out in the busy fall of 2021 renew this fall and through 2027, and those borrowers locked five-year fixed rates near 2 per cent.  A $700,000 mortgage taken at 2 per cent in the fall of 2021 carries a payment of about $2,964 and a balance today near $586,000, and renewed over the remaining 20 years at this week's best five-year fixed rate of 4.24 per cent, the payment becomes about $3,616, roughly $650 a month more.  CMHC reports that borrowers who renewed over the past eighteen months saw payments rise by an average of $375 a month (CMHC, cited by Money.ca, September 2026), and the 2021 cohort is starting from a lower rate than most of them did.

The big banks raised five-year fixed rates last week after the Canada five-year bond yield climbed to about 3.65 per cent, its highest since 2024 (Canadian Mortgage Trends, September 17 and 18, 2026), so if your renewal is within 120 days, get a written rate hold from your existing lender and at least one other today.  A hold costs nothing.  And do not sign the first renewal letter that arrives in the mail, because the rate printed on it is rarely the lender's best, and a broker who shops it can usually do better for a borrower with strong equity.

If you are buying or selling this fall

For buyers, lock a pre-approval with a rate hold and run your numbers at a half point above today's rate, so an October surprise does not change what you can afford.  For sellers, August showed inventory across the GTA tightening faster than sales, and more so here in Markham (TRREB Market Watch, August 2026), which still favours a well-priced listing, but October's buyers are carrying slightly higher borrowing costs than August's, so price to the last sixty days of sales rather than to the spring.

Whatever the Bank decides on October 28, the useful work happens before then: know your trigger rate if you are variable, get a rate hold if you renew or buy within four months, and shop the renewal rather than signing the letter.  A quarter point is manageable for almost every household I work with; being surprised by it is what causes trouble.  If you would like to run your own mortgage against these scenarios, call me and we will go through it together.
A $42,000 Toilet - Why Careful Condo Owners Can Still Be Handed the Building's Deductible

If you own a condo, whether you live in it or rent it out, a recent Ontario court decision should change how you think about the plumbing behind your walls.  Two Mississauga owners were held responsible for more than $42,000 in flood repairs, plus court costs, after a toilet in their tenanted unit overflowed, and the court did not need to find that they had been careless to reach that result (Bob Aaron, Toronto Star, September 21, 2026).  Here is what happened, why the law works the way it does, and the handful of checks I would make this week if any of this sounds familiar.

What happened in the Mississauga unit

Small Condo Bathroom with Toilet

Toronto Condo Bathroom

Early one morning in January 2022, the toilet in a rented unit on Trailwood Drive overflowed and water ran into the suite below, several neighbouring suites and the common elements.  When the superintendent arrived he found the flapper inside the tank sitting open, a blockage in the bowl, and a broken handle on the shut-off valve beside the toilet, which meant the tenants could not stop the water and he had to leave the suite to shut off the supply to the whole unit.  Two contractors repaired the damage for a combined $42,233.  The corporation's insurance deductible was $50,000, more than the entire loss, and its bylaw made an owner responsible for damage caused by an owner's or tenant's act or omission up to that deductible, so the corporation billed the owners for the full amount and, when they did not pay, registered a lien against the unit (Toronto Star, September 21, 2026, reporting the 2024 Ontario Superior Court decision of Justice Moiz Rahman).

Why careful owners can still be on the hook

The owners went to court to have the lien discharged, and the argument that matters to every condo owner in the province was this one: they said they had not been negligent, so they should not have to pay.  The court disagreed.  Following an earlier decision, Justice Rahman held that Ontario's Condominium Act does not require proof of negligence; the question is simply whether an act or omission by the owner or tenant caused the damage.  Two facts settled it.  Something had blocked the toilet, and the shut-off valve had not been maintained, so a problem that could have been stopped in seconds ran long enough to flood several suites.  The owners were responsible for maintaining both.  The lien stood, and on top of the $42,000 the owners were ordered to pay costs the column estimates at around $15,000, plus their own legal bill.

I want to be plain about what that means, because I hear the opposite assumption all the time from clients who own an investment unit.  Being a responsible owner who lives elsewhere and has never had a complaint is not a defence.  If a five-dollar part inside your unit fails and the damage spreads, the corporation's deductible is very likely coming to you, and deductibles of $25,000 to $50,000 or more are now common in newer towers, including the ones I see in Markham Centre and Unionville.

Four things to check this week

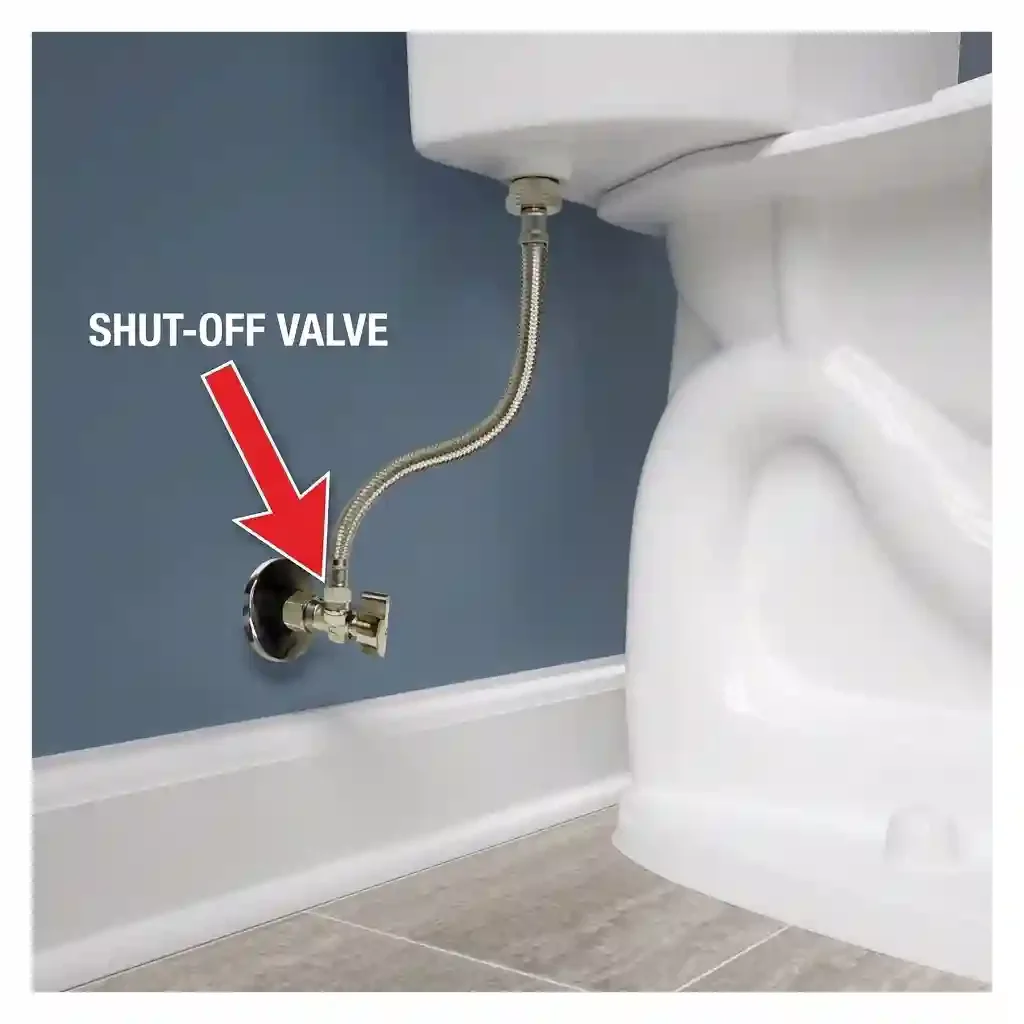
The first is the plumbing itself.  Every toilet and sink in your unit has a shut-off valve, and most owners have never turned one.  Turn each one, confirm it actually closes, and replace any that is stiff, corroded or broken, which is an inexpensive job for a plumber and, as this case shows, the difference between a mop and a lien.  While you are at it, have the toilet flappers and supply lines looked at; braided steel supply lines are cheap insurance against the rubber ones that fail without warning.

Toilet Shut-off valve placement

Typical Toilet Shut Off Valve

The second is your tenant, if you have one.  Show them where the shut-offs are and how to use them, put it in writing, and keep a copy.  The third is your own condo insurance.  Ask your broker two questions: does the policy cover the corporation's deductible in a loss caused by you, your guests, your tenant or a tradesperson, and does it cover lost rent or living expenses if the unit is uninhabitable during repairs.  Read the deductible coverage limit against the actual figure in your corporation's current certificate of insurance, because the limit that was fine when you bought may be well short of what the building now carries.  The fourth, and the one I insist on for any client leasing out a unit: never hand over keys without a copy of the tenant's own insurance policy in your file.

None of this is complicated, and all of it can be done in an afternoon, which is exactly why it gets put off.  A working shut-off valve, a tenant who knows where it is, and a policy that covers the building's deductible are what stand between a routine plumbing failure and a five-figure charge registered against your unit.  If you own a condo and want a second opinion on what your corporation's deductible means for you, or you are weighing whether to keep the unit as a rental or sell it into this fall's market, call me and we will go through it.

Source The Toronto Star Sept 21 2026 Bob Aaron / CanLii

Ontario's Rental Rules Change on September 21 - What Landlords and Sellers Need to Know

Unionville Rental Condo - Tridel

If you own a rental condo, a basement apartment or an investment townhouse anywhere in Markham, the rules that govern your relationship with your tenant change on Sunday, September 21.  The changes come from the second wave of Bill 60, the Fighting Delays, Building Faster Act, 2025, and they touch three things that come up constantly in my work: how quickly a landlord can act on unpaid rent, what happens at a hearing, and what it costs to reclaim a unit for your own family.  Here is what changes, and what I would do about it whether you are a landlord, a tenant, or someone buying or selling a home with a tenant in place.

The N4 window drops from 14 days to 7

The headline change is the notice for non-payment of rent.  Since the Residential Tenancies Act came into force, a landlord serving an N4 on a monthly tenant has had to give 14 days for the rent to be paid before an application could be filed with the Landlord and Tenant Board.  For any N4 served on or after September 21, that termination period becomes 7 days (Tribunals Ontario operational update, June 30, 2026; Bill 60, Royal Assent November 27, 2025).  Two details matter.  The 7-day period applies only to notices served on or after the 21st, and an N4 served before that date with a 7-day termination date is void, so if you are dealing with arrears right now, use the current form and the current 14 days.  And the notice is still only the first step; it opens the door to an L1 application, it does not end a tenancy on its own.

Persistent late payment gets a definition

Until now, "persistently late" was left to adjudicators to weigh case by case.  From September 21, the regulation defines it, and the working test is failing to pay rent within seven days of the due date on at least three occasions within a six-month period, subject to the conditions set out in the regulation (Ontario RTA amendments under Bill 60, effective September 21, 2026).  For a landlord in Markham whose tenant is chronically a week or two behind but always eventually pays, that is a meaningful change, because the pattern itself now has a legal name.  For tenants, it is a plain warning that paying on the 9th or 10th every month is no longer a harmless habit.

What changes at a hearing

Two procedural changes will matter more than they sound.  First, at a non-payment hearing, a tenant who wants to raise their own issues in response, such as maintenance complaints under section 82 of the Act, must first pay half of the arrears claimed, at least seven days before the hearing.  A tenant can still bring maintenance problems forward in a separate application, but the days of a repair dispute stalling an arrears hearing indefinitely are, in principle, over.  Second, and this is the change I want every downsizer and every parent with an adult child moving home to understand: when a landlord serves an N12 to reclaim a unit for their own use or a family member's use under section 48, the one month of compensation that has been mandatory is waived if the landlord gives at least 120 days' notice instead of the usual 60.  Give the tenant four months rather than two and the one-month payment falls away.

There is a wrinkle that matters if you are selling.  The waiver applies only to a landlord's own-use N12.  When a buyer purchases a tenanted property and needs the unit for themselves, that notice is served under section 49, and the one-month compensation still applies (Bill 60 implementation guidance, OntarioLandlord and PowerHouse Property Management summaries, 2026).  A seller who tells a buyer the tenant can be moved out for free is giving them the wrong information, and I would rather you hear that from me than at closing.

What I would do

If you are a landlord, update your forms and your calendar.  Use the new N4 only from September 21, keep a written record of every late payment from now on because the six-month clock on persistent lateness is now something you can prove, and if you have been thinking of taking a unit back for family, the 120-day route is worth the extra two months of patience.  If you are a tenant, pay on the day rent is due and keep your own records, because the margin for error has narrowed.  If you are buying or selling a tenanted condo in Markham, build the tenancy into the offer properly: the correct notice, the correct compensation, and a closing date that respects both.  I am not a lawyer and none of this replaces advice from one; for anything contested, a paralegal or lawyer who works at the Board every week is money well spent.

The rules governing Ontario rentals tighten on September 21, and the changes mostly favour landlords who keep good records and act correctly.  Update your forms, document your payments, and understand which N12 you are actually serving before you promise anyone a vacant unit. 


• Bill 60, Fighting Delays, Building Faster Act, 2025 (Royal Assent November 27, 2025): https://www.ola.org/en/legislative-business/bills/parliament-44/session-1/bill-60

• Tribunals Ontario operational update confirming the September 21, 2026 effective date (June 30, 2026): https://tribunalsontario.ca/ltb/

August 2026 TRREB Numbers: Markham's Fall Market Is Tighter Than It Looks

The August numbers from the Toronto Regional Real Estate Board came out last week, and the line most people saw was that the average GTA selling price slipped back under a million dollars.  That is true, and it is also the least useful number in the release.  The figure that actually tells you what this fall will feel like in Markham sits underneath it: new listings fell close to seven times faster than sales did, which means the wide selection buyers have enjoyed all year is quietly disappearing.

Fewer sellers, not fewer buyers

Across the GTA in August there were 5,057 sales, down 2.1 per cent from a year earlier, which is a modest dip and roughly what I would expect in a hot, quiet month when families are away.  New listings came in at 12,075, down 14.1 per cent, and active listings at the end of the month sat at 24,482, down 11.3 per cent from last August (Toronto Regional Real Estate Board, Market Watch, released September 3, 2026).  Read those three together and you get a market where sellers stepped back considerably harder than buyers did.

That is a meaningful turn.  For most of this year the leverage sat with buyers, and it sat there for one reason: they had options, and they knew it.  A buyer who could walk away from a house because three similar ones were sitting a few streets over was a buyer who could negotiate.  When the supply of comparable homes thins out, that leverage thins out with it, quietly and without any announcement.

What the Markham numbers say

York Region recorded 971 sales in August at an average price of $1,179,938, and within the region Markham averaged $1,208,692 (TRREB August 2026 community figures).  Prices are still softer than a year ago - the GTA average was down 2.7 per cent, and the MLS Home Price Index, which adjusts for the mix of what actually sold, was down 4.5 per cent - so I am not going to tell you values are climbing, because they are not.  What is changing is the competition, and competition is what sets the tone of a negotiation.  A detached home in Berczy or Wismer listed in October will have fewer comparable homes sitting beside it than the same house would have had in May, and that difference shows up in how confident a buyer feels about pushing on price.

If you are selling this fall

The first thing I would do is price to the last sixty days rather than to the spring, because with the index down 4.5 per cent year over year, a comparable sale from April is telling you a story that has already ended.  The second is to take presentation seriously.  Homes across the GTA took an average of 35 days to sell in August, and in a market with a modest buyer pool, the listing that photographs well and shows well is the one that gets the early attention while the others wait.  Thinner inventory helps you, but it does not rescue an optimistic price.  It simply means an honestly priced home now has a better chance of being the obvious choice rather than one of six.

If you are buying

The instinct right now is to wait, on the theory that more homes and better prices are coming.  I would be careful with that.  The Bank of Canada held its policy rate at 2.25 per cent on September 2, so borrowing costs are steady for the moment, and steady rates paired with shrinking inventory is the combination that historically ends a buyer's market rather than extends it.  November and December in Markham are not seasons of abundant choice; they are the quietest listing months of the year.  If you have seen a home this month that genuinely works for your family, the selection you are holding out for may not arrive before spring, and by spring you may be competing for it.

Our Thoughts

August was not a strong month for prices, but it was a clear month for direction: supply is contracting faster than demand, and that is what tightens a market.  If you are selling, price to recent evidence and use the thinner competition to your advantage rather than as an excuse to reach.  If you are buying, treat this fall as a narrowing window rather than a widening one.  If you want to know what this looks like on your specific street, I am happy to pull the recent sales and walk you through them - the neighbourhood picture is often quite different from the regional headline.

Listed to Closed in 31 Days

43 Cornell Common sold in fourteen days and closed thirty-one days after it was listed. 
It sold over asking, and the buyers had keys inside a single calendar month.

The close timeline was negotiated - the buyers wanted possession quickly and our sellers were able to work with it.  That part isn't standard, and we won't pretend it is.  What is repeatable is everything that happened before the offer came in.

Bank of Canada Holds Key Rate at 2.25%

The Bank of Canada left its policy rate at 2.25 per cent this morning, which is the outcome nearly everyone expected.  But if you are buying in Markham this fall, or you have a mortgage coming up for renewal, the rate the Bank announced is not the number that will decide what your payment looks like.  The number that matters is the bond yield sitting behind fixed mortgage rates, and that one has been climbing quietly all summer while the Bank has stayed still.

What the Bank actually said

The statement itself was measured.  CPI inflation has been hovering around 3 per cent in recent months, driven mainly by persistently higher gasoline prices, while the core measures the Bank watches most closely have stayed near its 2 per cent target.  At the same time the economy came in stronger than the Bank had penciled in, with second quarter GDP up 3.3 per cent against a forecast closer to 2.5 per cent.  Set against that, new American tariffs and Canadian counter-measures were announced after trade talks between the two countries broke down, which cuts the other way entirely.  Governing Council closed by saying it will assess the sustainability of the economic rebound and the outlook for inflation, and is prepared to adjust monetary policy as needed.  That is deliberately non-committal language, and it is worth reading it as exactly that.

Why fixed rates can rise while the Bank sits still

This is the part that catches people off guard every time, so it is worth being plain about it.  Your variable rate and your line of credit are tied to prime, which sits at 4.45 per cent and does not move on a hold, so if you are carrying a variable mortgage today nothing changed for you this morning.  Fixed rates work differently.  They follow the bond market, and the Government of Canada five and ten year yields have been drifting upward since early July, with the ten year now around 3.74 per cent after a move of roughly 36 basis points.  Lenders price fixed mortgages off those yields, not off the overnight rate, which is why you can have a central bank standing perfectly still and a fixed rate quote that is meaningfully worse than the one you were given in June.

The other shift is in expectations.  For most of the past two years the conversation in this market has been about when the next cut arrives.  That conversation has changed.  Roughly 63 per cent of analysts surveyed now expect the Bank's next move to be upward rather than downward, most of them pointing to the first half of 2027, and a couple of the big banks have floated the possibility of an increase as early as October.  I am not telling you to treat that as a forecast, because these calls move around constantly and the tariff picture could turn again.  I am telling you that planning around a cut that may never come is a weaker position than it was a year ago.

What this means for Markham specifically

Our local market is tighter than the national headlines suggest.  Markham recorded 288 sales in July at an average price of $1,131,324 and a median of $1,062,500, with a sales to new listings ratio of 39.4 per cent, the tightest in York Region.  Fewer sellers came out this summer than in the past couple of years, so the well prepared, sensibly priced home is facing less resale competition heading into the fall than it did last September.  For a buyer in Unionville, Cachet, or Berczy, that means the inventory advantage you may have been counting on is thinner than you think, and waiting has a cost on both sides of the ledger now.

What I would actually do

If you are buying, get your pre-approval refreshed this week rather than next month, and hold the rate while you can, since most lenders will guarantee a quoted fixed rate for 90 to 120 days and that hold costs you nothing if rates fall.  If you are renewing in the next year, start shopping four to six months ahead instead of waiting for the letter from your lender, and get a second quote before you sign the one in front of you.  And if you are selling, price against the last ninety days of comparable sales rather than what your neighbour got in a different rate environment, because buyers in this market are doing the payment math carefully and they will notice.

The Story

The hold is not the story.  Fixed mortgage rates are being pushed up by bond yields even while the Bank sits at 2.25 per cent, and the market's expectation has quietly flipped from the next cut to the next increase.  If you are buying or renewing in Markham this fall, lock a rate hold now and plan on today's numbers rather than a cut that may not arrive.

If you want to talk through what this means for your own timing, call any time.  Over the years we have walked a lot of Markham families through decisions exactly like this one, and it is always easier with the actual numbers in front of you.

Sources: Bank of Canada policy rate announcement, September 2, 2026; Canadian Mortgage Trends, September 2026; Toronto Regional Real Estate Board July 2026 market data.

What Ontario's HST Rebate on New Homes Means for Markham Sellers This Fall

If you are planning to sell a detached home or a freehold townhouse in Markham this fall, the thing that has changed most is not the interest rate, it is who you are competing against.  Ontario's expanded HST rebate applies only to newly built homes, and over the summer it has pulled a meaningful share of buyers toward builder inventory, with single-family new home sales across the GTA finishing July up 246% over the same month a year ago.  What follows is what that shift does to your pricing and your marketing, and where an established Markham home still holds a real advantage.

The July numbers, and why they are unusual

Builders sold 1,018 new homes across the GTA in July, and 781 of those were single-family: detached, semi-detached, linked and townhomes.  That puts the single-family category roughly 50% above its ten-year July average, which is a genuinely unusual reading in a market most people still describe as slow.  At the same time, the benchmark price on those new single-family homes was $1,362,433, down 8.5% from a year ago, while new condominium apartments sold 80% below their ten-year average (source: BILD and Altus Group new home sales release for July 2026, published August 27).

I read those two facts as one story rather than two.  Builders have been discounting, the rebate stacks on top of the discount, and buyers who spent the last two years waiting have decided that the combination is finally worth acting on.  Dave Wilkes at BILD described it as the fourth consecutive month of positive momentum in the single-family category, and the pattern in the numbers supports him.

The part that catches resale sellers off guard

The rebate does not apply to a resale home.  When a buyer sits down and compares your house in Markham Village, Unionville or Cornell against a new release a few minutes up the road, they are weighing your asking price against a builder's price less a rebate that can reach well into five or six figures, and that arithmetic can look unflattering if you have anchored your expectations to what a neighbour achieved in a different market.  I would far rather you hear this from me in early September than work it out for yourself in late October, after a month of polite showings and no offers.

This is not a reason to be discouraged, and it is certainly not a reason to give the house away.  It is a reason to price and present against what is actually on the market right now instead of against memory.

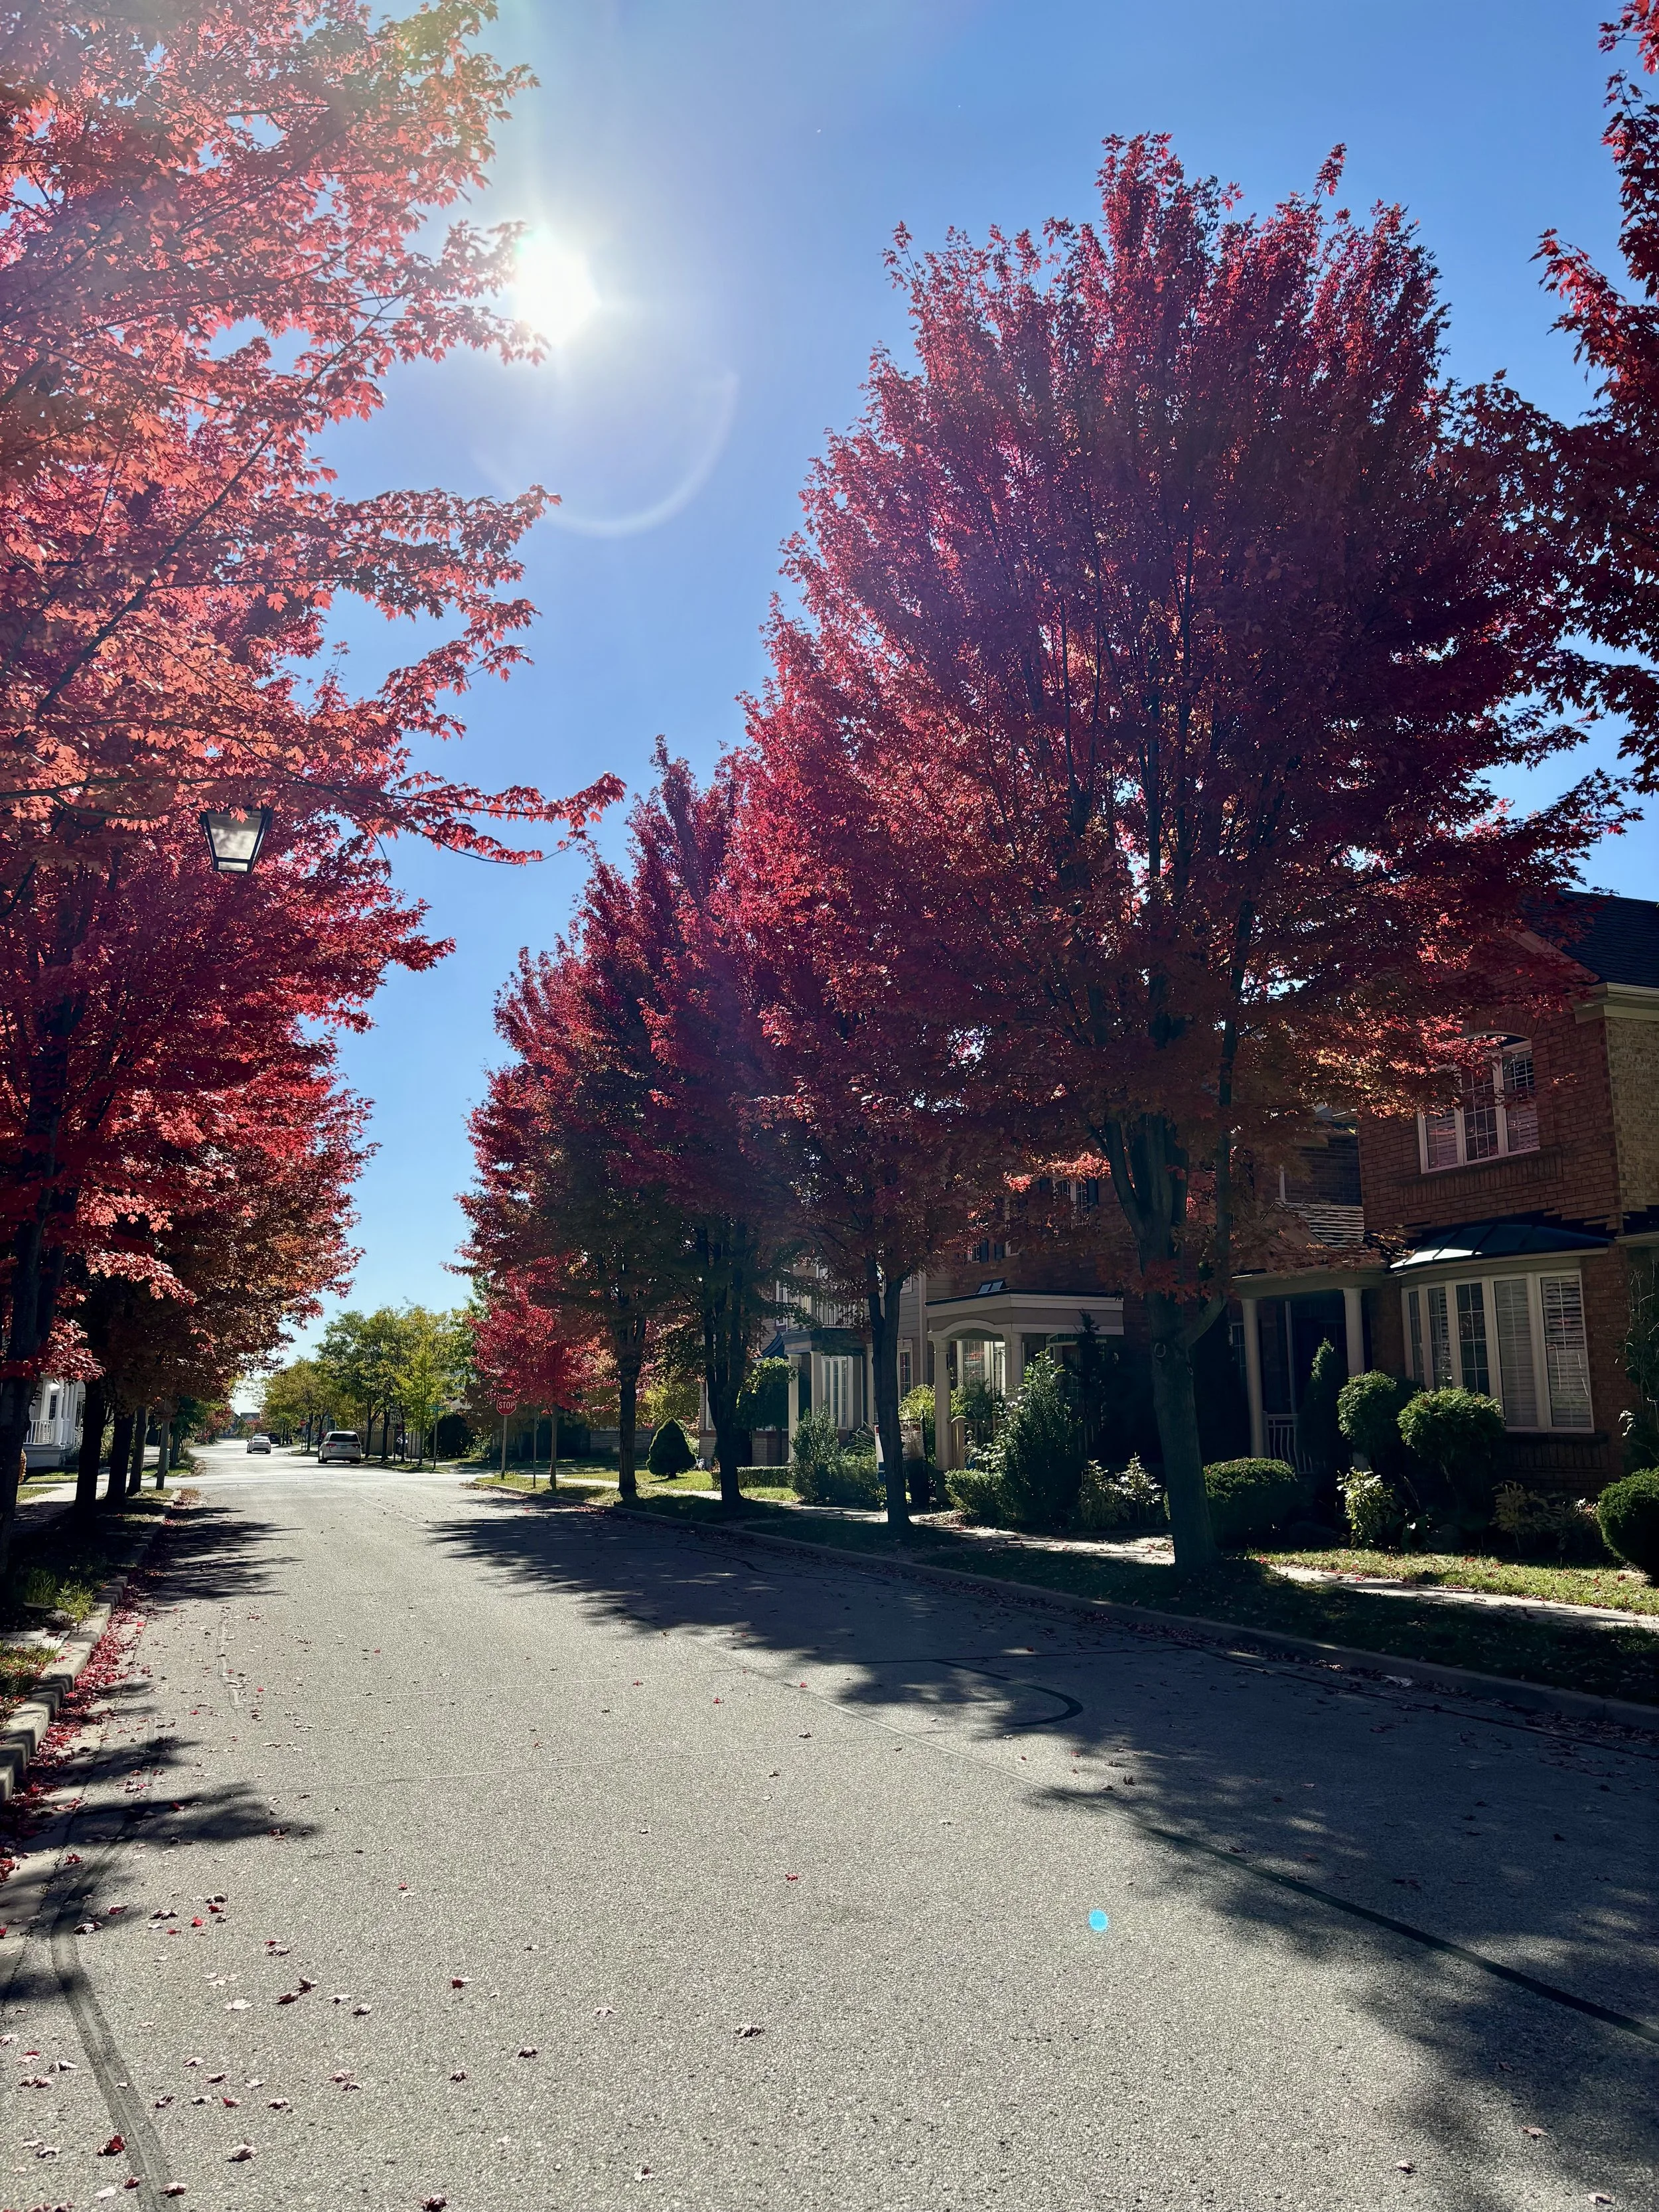
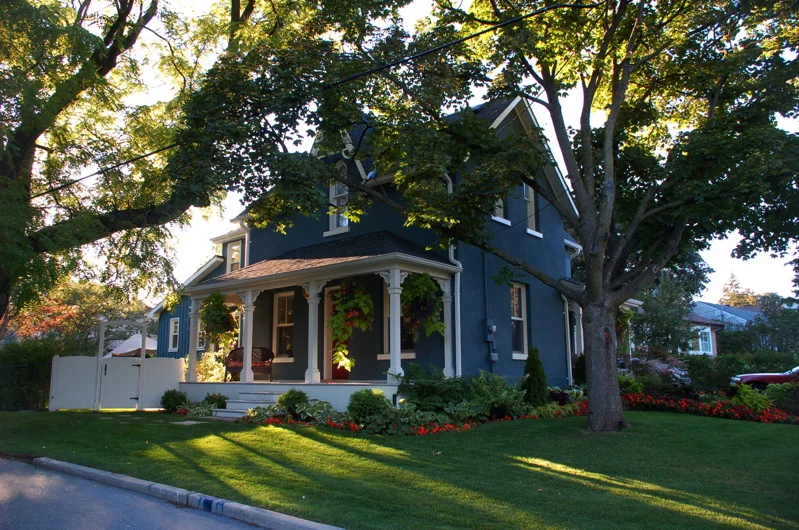
Mature Tree Lined Street in Markham

Mature Tree Lined Street in Markham

Where an established Markham home still wins

A new build is a floor plan and a rendering, and for a lot of buyers that is exactly the appeal.  But an established home in Unionville, Markham Village, Berczy, Wismer, Swan Lake or Cornell offers a set of things a builder simply cannot put in a brochure: mature trees and finished landscaping that would take fifteen years to grow in, a school assignment that is settled today rather than promised, a closing date you can actually plan a move around, and no development charge adjustments or occupancy delays waiting at the end of the process.  There is also no HST on the purchase price of a resale home, which is worth saying plainly to any buyer who has been doing the builder math and has not thought it through.

When I take a listing in one of these neighbourhoods, that is the conversation I want the marketing to be having.  Photograph the mature canopy, the established gardens, the finished basement that a new owner would otherwise spend a year and a great deal of money creating.  Sell the fifteen years the buyer does not have to wait.

How I would price into this market

Markham itself is holding up better than the headlines suggest.  There were 288 sales here in July at an average price of $1,131,324 and a median of $1,062,500, with a sales-to-new-listings ratio of 39.4%, the tightest in York Region, and roughly 4.2 months of inventory.  Across York Region as a whole, new listings were down 18.7% from a year ago (source: TRREB Market Watch, July 2026).  Fewer sellers came to market this summer, which means a well-prepared, sensibly priced home is facing less resale competition than it would have faced last fall, even with the builders active.

So the strategy is not complicated.  Price against the last ninety days of sales on streets genuinely comparable to yours, not against a builder's list price and not against 2022.  Prepare the home properly before it goes live rather than after.  And get out in front of the fall traffic, because the Bank of Canada announces its next rate decision on Wednesday, September 2, and the buyers who have been waiting on that news will be looking the following weekend.

The Buyer’s Advantage

The HST rebate has given builders an advantage on price that a resale seller cannot match dollar for dollar, so do not try to.  Compete instead on the things an established Markham neighbourhood already owns: mature setting, certainty, and a closing you can plan around, priced honestly against the last ninety days.  If you are thinking about a fall sale, I am glad to walk through your home, tell you candidly what is worth doing and what is not, and put real local numbers behind the pricing conversation.

Brad

The Zoning on That Listing May Be Out of Date - What's Changing Across York Region

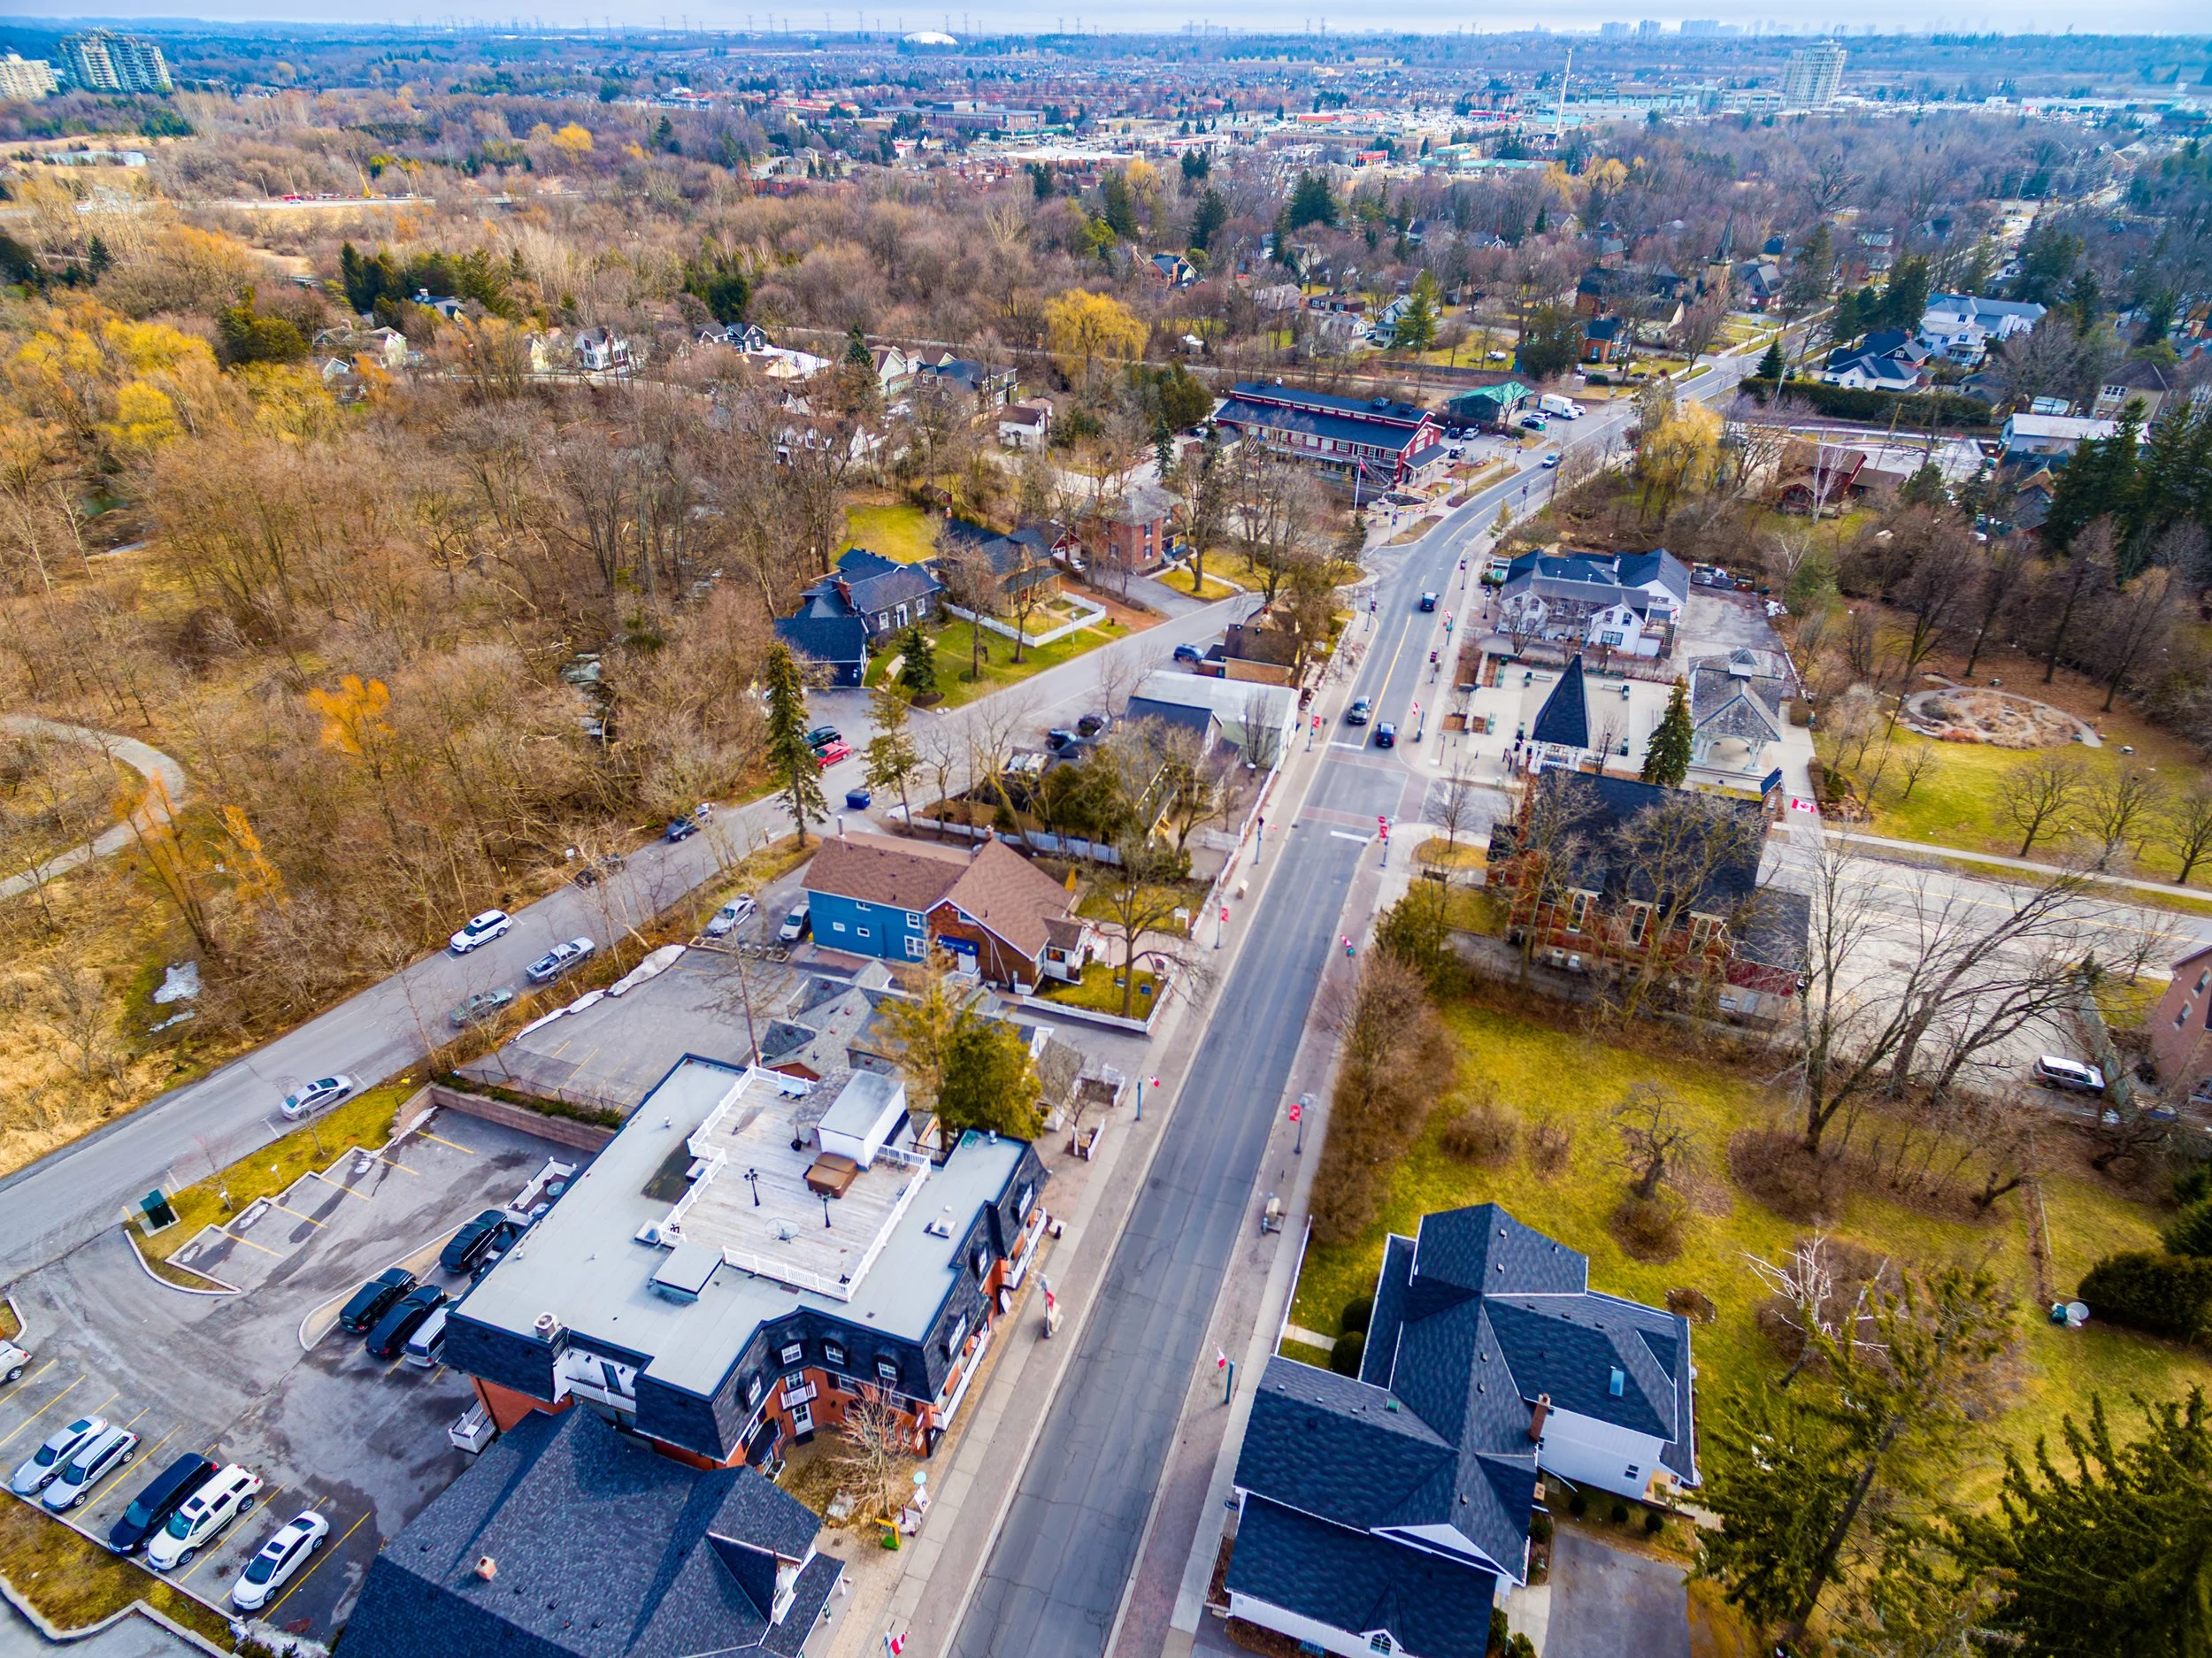
Aerial View of Unionville Main Street

Aerial view of Main Street Unionville © Brad Macdonald

If you are buying a property in York Region for what you plan to do with it, whether that is a second unit for family, a workshop, or a future severance, confirm the zoning with the municipality itself before your conditions come off.  Three municipalities here have rewritten or are rewriting their zoning by-laws at more or less the same time, and the property databases that agents and lawyers pull from have not all kept pace.  The acreage on the deed does not change; what you are permitted to build on it can.

Markham's rewrite is already finished

Council enacted a new comprehensive zoning by-law, By-law 2024-19, on January 31, 2024, and the Ontario Land Tribunal approved it on a city-wide basis on September 19, 2024, save for lands tied to remaining site-specific appeals (source: yourvoicemarkham.ca).  What it replaced is remarkable when you see it written down: forty-six separate parent zoning by-laws, enacted between 1954 and 2004, each with its own definitions and standards.  For most Markham homeowners this was overdue housekeeping and nothing more.  But if you are working from an older listing, an older survey, or a report prepared before 2024, the zoning it names may simply no longer exist, and a small number of properties do still sit under the older rules. Some of the biggest changes occur to the commercial/industrial zoning around Markham’s inclusive industrial zone just east of McCowan road, by CF Markville, with the official plan designating some of this for ‘future redevelopment’ with very different zoning.

Georgina is partway through, and rural buyers should care most

Georgina's Countryside lands, meaning the rural and agricultural areas outside the settlement boundaries, now fall under Countryside Zoning By-law 600, while Keswick, Sutton, Jackson's Point, Pefferlaw and the hamlets remain under the older By-law 500.  Phase two, which updates the settlement areas, began in 2025 and is expected to conclude in 2027 (source: Town of Georgina, Zoning By-law Update).  For anyone shopping in cottage country the practical consequence is significant.  A large rural parcel that once appeared simply as rural may now carry a combination of designations, with Environmental Protection applied to a portion of it.  The land has not shrunk by a square foot, but where you may build, whether an additional dwelling unit is permitted, and what a severance might realistically look like can all have changed.

Stouffville is next

Whitchurch-Stouffville still operates under Comprehensive Zoning By-law 2010-001-ZO, consolidated as recently as July of this year, while its ReZone and ReDesign project works toward an updated by-law and new urban design guidelines (source: townofws.ca).  Nothing has flipped yet, which makes this the right moment for anyone with plans for a Stouffville property to pay attention rather than to assume.

The part almost nobody checks

The property information services that agents and lawyers pull from, and the assessment records behind them, do not always reflect these transitions right away.  You can look a property up in perfectly good faith and be handed a zoning designation that was superseded a year or more ago.  Nobody is being careless about it.  Municipal by-laws simply change faster than the databases that describe them, and there is no flag on the screen telling you that what you are reading is out of date.

So before zoning becomes the reason you are buying a property, confirm it at the source: the municipality's own current zoning map and by-law schedules, not a listing sheet, not an old report, and not the property's historical use.  Look specifically for whether the parcel carries more than one designation, and for site-specific exceptions, which are common and easy to miss.  If your plan depends on the answer, a call to the municipal planning department before the conditions come off is the cheapest insurance you will ever buy, and if the answer is still unclear, that is exactly what a properly drafted condition in your offer is for.

Always Confirm Zoning

Zoning across York Region is in transition, and the record you look up may not be the record that governs the property.  Confirm the current zoning with the municipality before you waive conditions on anything you are buying for its development potential, and treat rural and large-lot parcels as the highest risk.  Over the years I have found that the expensive surprises are almost never about price; they are about what someone assumed they could do with a property and then could not.

If you are considering a rural or large-lot purchase anywhere in York Region this fall and want a second set of eyes on it before you commit, call me.  I would far rather spend an afternoon on this with you than help you unwind it later.

Getting Your Markham Home Ready for a Fall Sale: A Late-August Checklist

Every year around this time, I get the same call: "We're thinking of selling this fall - when should we start getting ready?"

And every year my answer is the same: now.

Not because there's any panic in it, but because the sellers who do well in the fall market are the ones who spend late August preparing while everyone else is still at the cottage.

Here's the checklist I walk my own clients through, refined over years of Markham falls.

Take your exterior photos now. This is the one people most often miss. The serious fall buyers show up the week after Labour Day, but if you list in late September or October, your hero shot gets taken under grey skies and bare branches. Photograph the outside of your home in the next two or three weeks, while the gardens are full and the trees are green. A great late-August exterior photo will carry a November listing. If you're in Unionville, Markham Village or an established pocket like Swan Lake where mature trees and gardens are half the charm, this matters double.

Deal with the small stuff. Buyers in a market like this one are choosier than they were a few years ago, and small flaws read as neglect. Sticky doors, chipped trim, the downspout that's leaned since spring, caulking around tubs and sinks - a weekend and a few hundred dollars here protects tens of thousands in perceived value.

Service what buyers will ask about. Have the furnace serviced and keep the receipt. Clean the eavestroughs. If your roof, windows or A/C are newer, gather the paperwork. Fall buyers are walking into their first heating season; proof that the house is ready for it is quiet, powerful reassurance.

Declutter with moving boxes, not garbage bags. You're moving anyway, so start now. Pack away a third of what's in your closets and half of what's on your surfaces. Rooms photograph larger, and buyers can see the house instead of the household.

Price to this fall, not to memory. The GTA average price sat at $1,003,956 in July, about 4.5% below a year ago - but new listings were down almost 18%, which means well-priced homes face less competition than last fall (source: TRREB Market Watch, July 2026). The winning strategy in this market is pricing against the last 90 days of sales on streets like yours, then letting the tight supply do its work. Anchoring to a 2022 number is how good homes go stale.

Know your buyer. In Berczy and Wismer, fall buyers are often families who want to close in time to settle before the next school year decisions. In Cornell, it's a mix of first-time buyers and young families watching rates. Around Main Street Unionville, it's lifestyle buyers - and honestly, the village sells itself in autumn; there's no better season to show it. Y our preparation, staging and timing should match who's actually coming through the door.

If a fall sale is even a maybe for you, late August is when the groundwork happens. I'm happy to walk through your home, tell you honestly what's worth doing (and what isn't), and put real local numbers behind a pricing conversation. No obligation - just years of Markham falls put to work for you.

Brad

Main Street Unionville Has Its Sparkle Back - and Jazz Festival Weekend Is the Time to See It

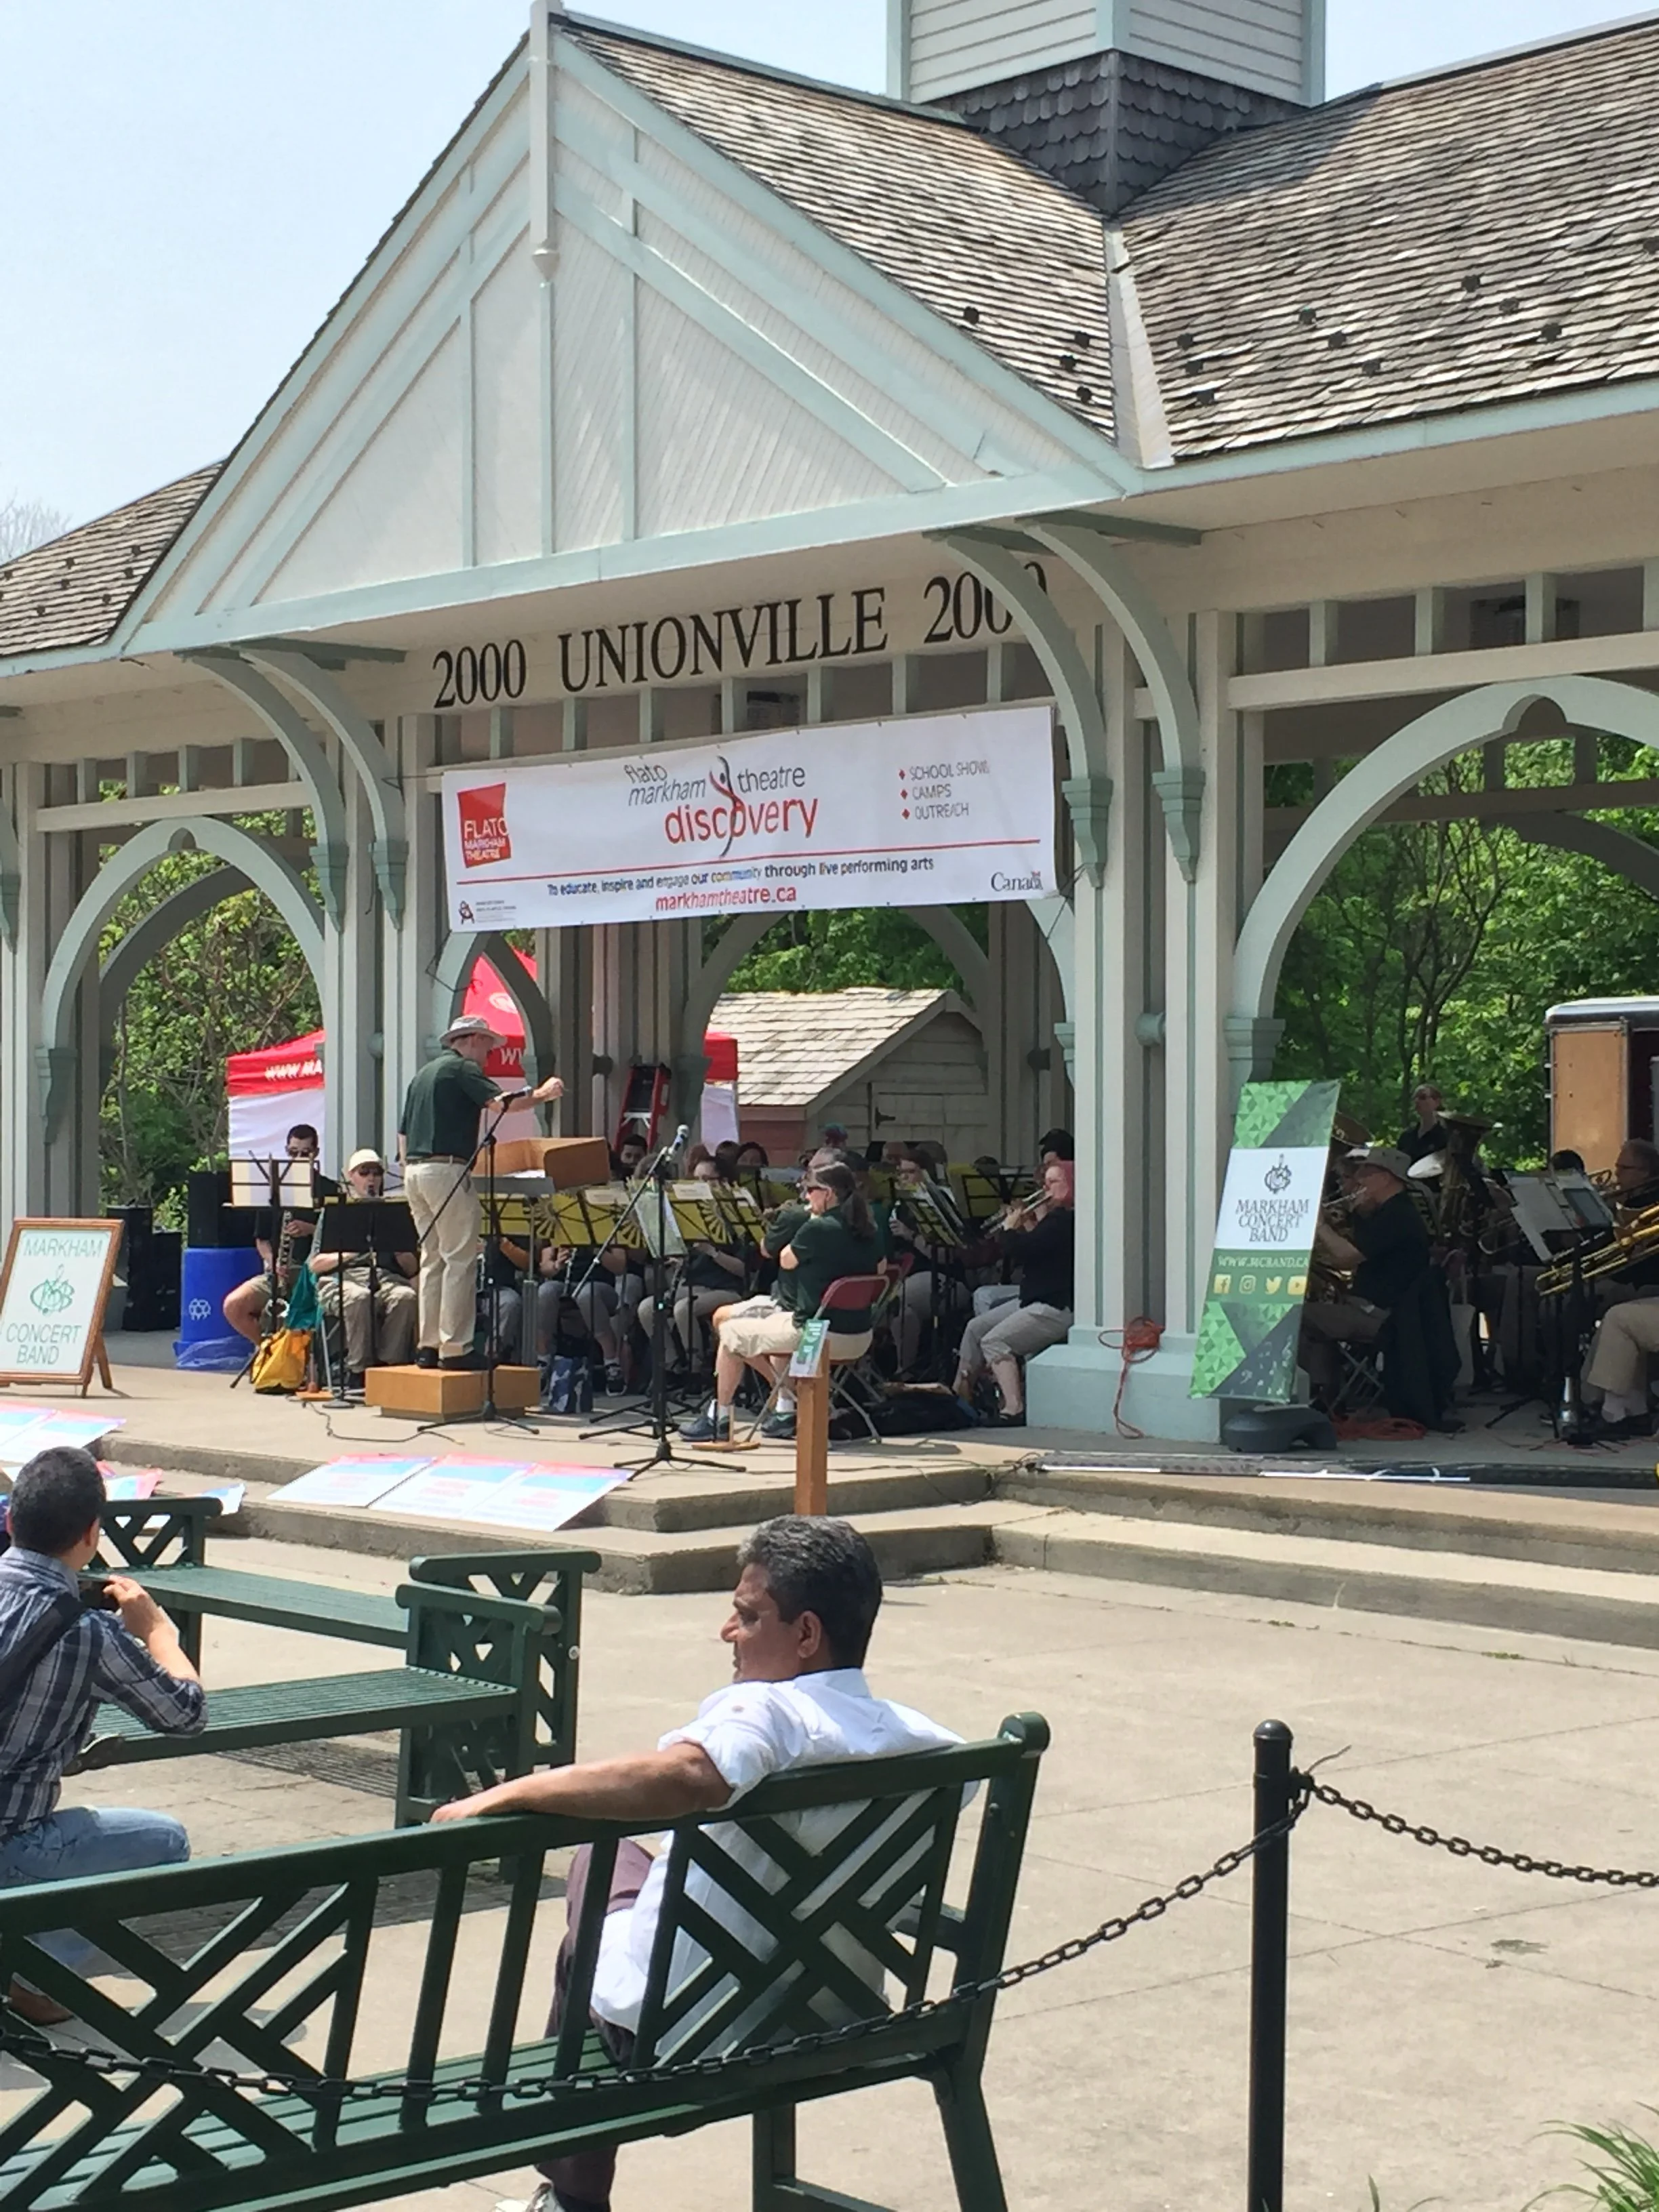
The Unionville Bandshell

If you had tried to stroll Main Street Unionville on a Saturday last summer, you'd have been dodging fencing, gravel and construction hoarding.  The village spent the better part of two years dug up while the street was rebuilt, and I'll admit that even I - and I've watched this community through every kind of change since the 1980s - wondered how the shops and restaurants would weather it.

This spring we got our answer.  On May 31, the city officially reopened Main Street after a $14.8 million restoration, funded jointly by Markham and the federal government, that renewed the street's infrastructure and streetscape while protecting the heritage character that makes the village what it is (source: City of Markham; CBC News, May 31, 2026).  Mayor Frank Scarpitti put it well at the reopening: this street carries nearly 200 years of history, and the point of the investment was to celebrate that history, not pave over it.  Walk it today and you can feel the difference underfoot - the street is whole again, the patios are full, and the businesses that held on through construction are finally being rewarded.

This coming weekend is the perfect excuse to go see for yourself.  The Markham Jazz Festival returns August 22 and 23 for its 29th year, filling the village with live music from Main Street down to the Varley Art Gallery (source: markhamjazzfestival.com).  If you've never spent a festival evening in Unionville, with music drifting past century-old storefronts and the crowds wandering up from Toogood Pond, it's the best introduction to this neighbourhood I know.  Come early, because parking fills quickly, and the walk in from the surrounding streets is honestly part of the charm.

Now let me put my broker hat on, because there's a real estate story here that outlasts the weekend.

We've been selling homes in and around Unionville since 1986, and one lesson has held through every market: public investment in a neighbourhood's bones shows up in its property values, slowly and then all at once.  A street that has just had its infrastructure renewed for the next generation is a street whose biggest capital questions are answered for decades to come.  Buyers rarely price that in consciously, but they feel it the moment they walk the village, and over the years I've watched that feeling translate into steady demand for every pocket within walking distance: the heritage homes off Main Street itself, the mature crescents around Toogood Pond, and the family streets that feed into the village from Carlton Road and Kennedy.

For sellers in the village, the timing is worth understanding.  Homes near Main Street trade rarely - families arrive and stay for decades, which is the best endorsement a neighbourhood can get, but it also means each listing is its own event with little direct competition.  With the construction finally behind us and the street showing at its absolute best, this fall is as strong a backdrop for an Unionville listing as I've seen in years, provided the price reflects today's market rather than a 2022 memory.

For buyers, my advice is to be patient and be ready at the same time.  The right house near the village doesn't come along on your schedule, and when it does, you'll be competing with people who have waited just as long as you have.  Knowing your numbers before that day - what you can carry, what the street's recent sales actually say - is what turns a near miss into a new address.

Either way, start with a walk.  Come for the jazz on Saturday, stay for dinner on a patio, and see what $14.8 million and 200 years of history look like together.  And if the village gets under your skin the way it got under mine all those decades ago, you know where to find me.

Brad

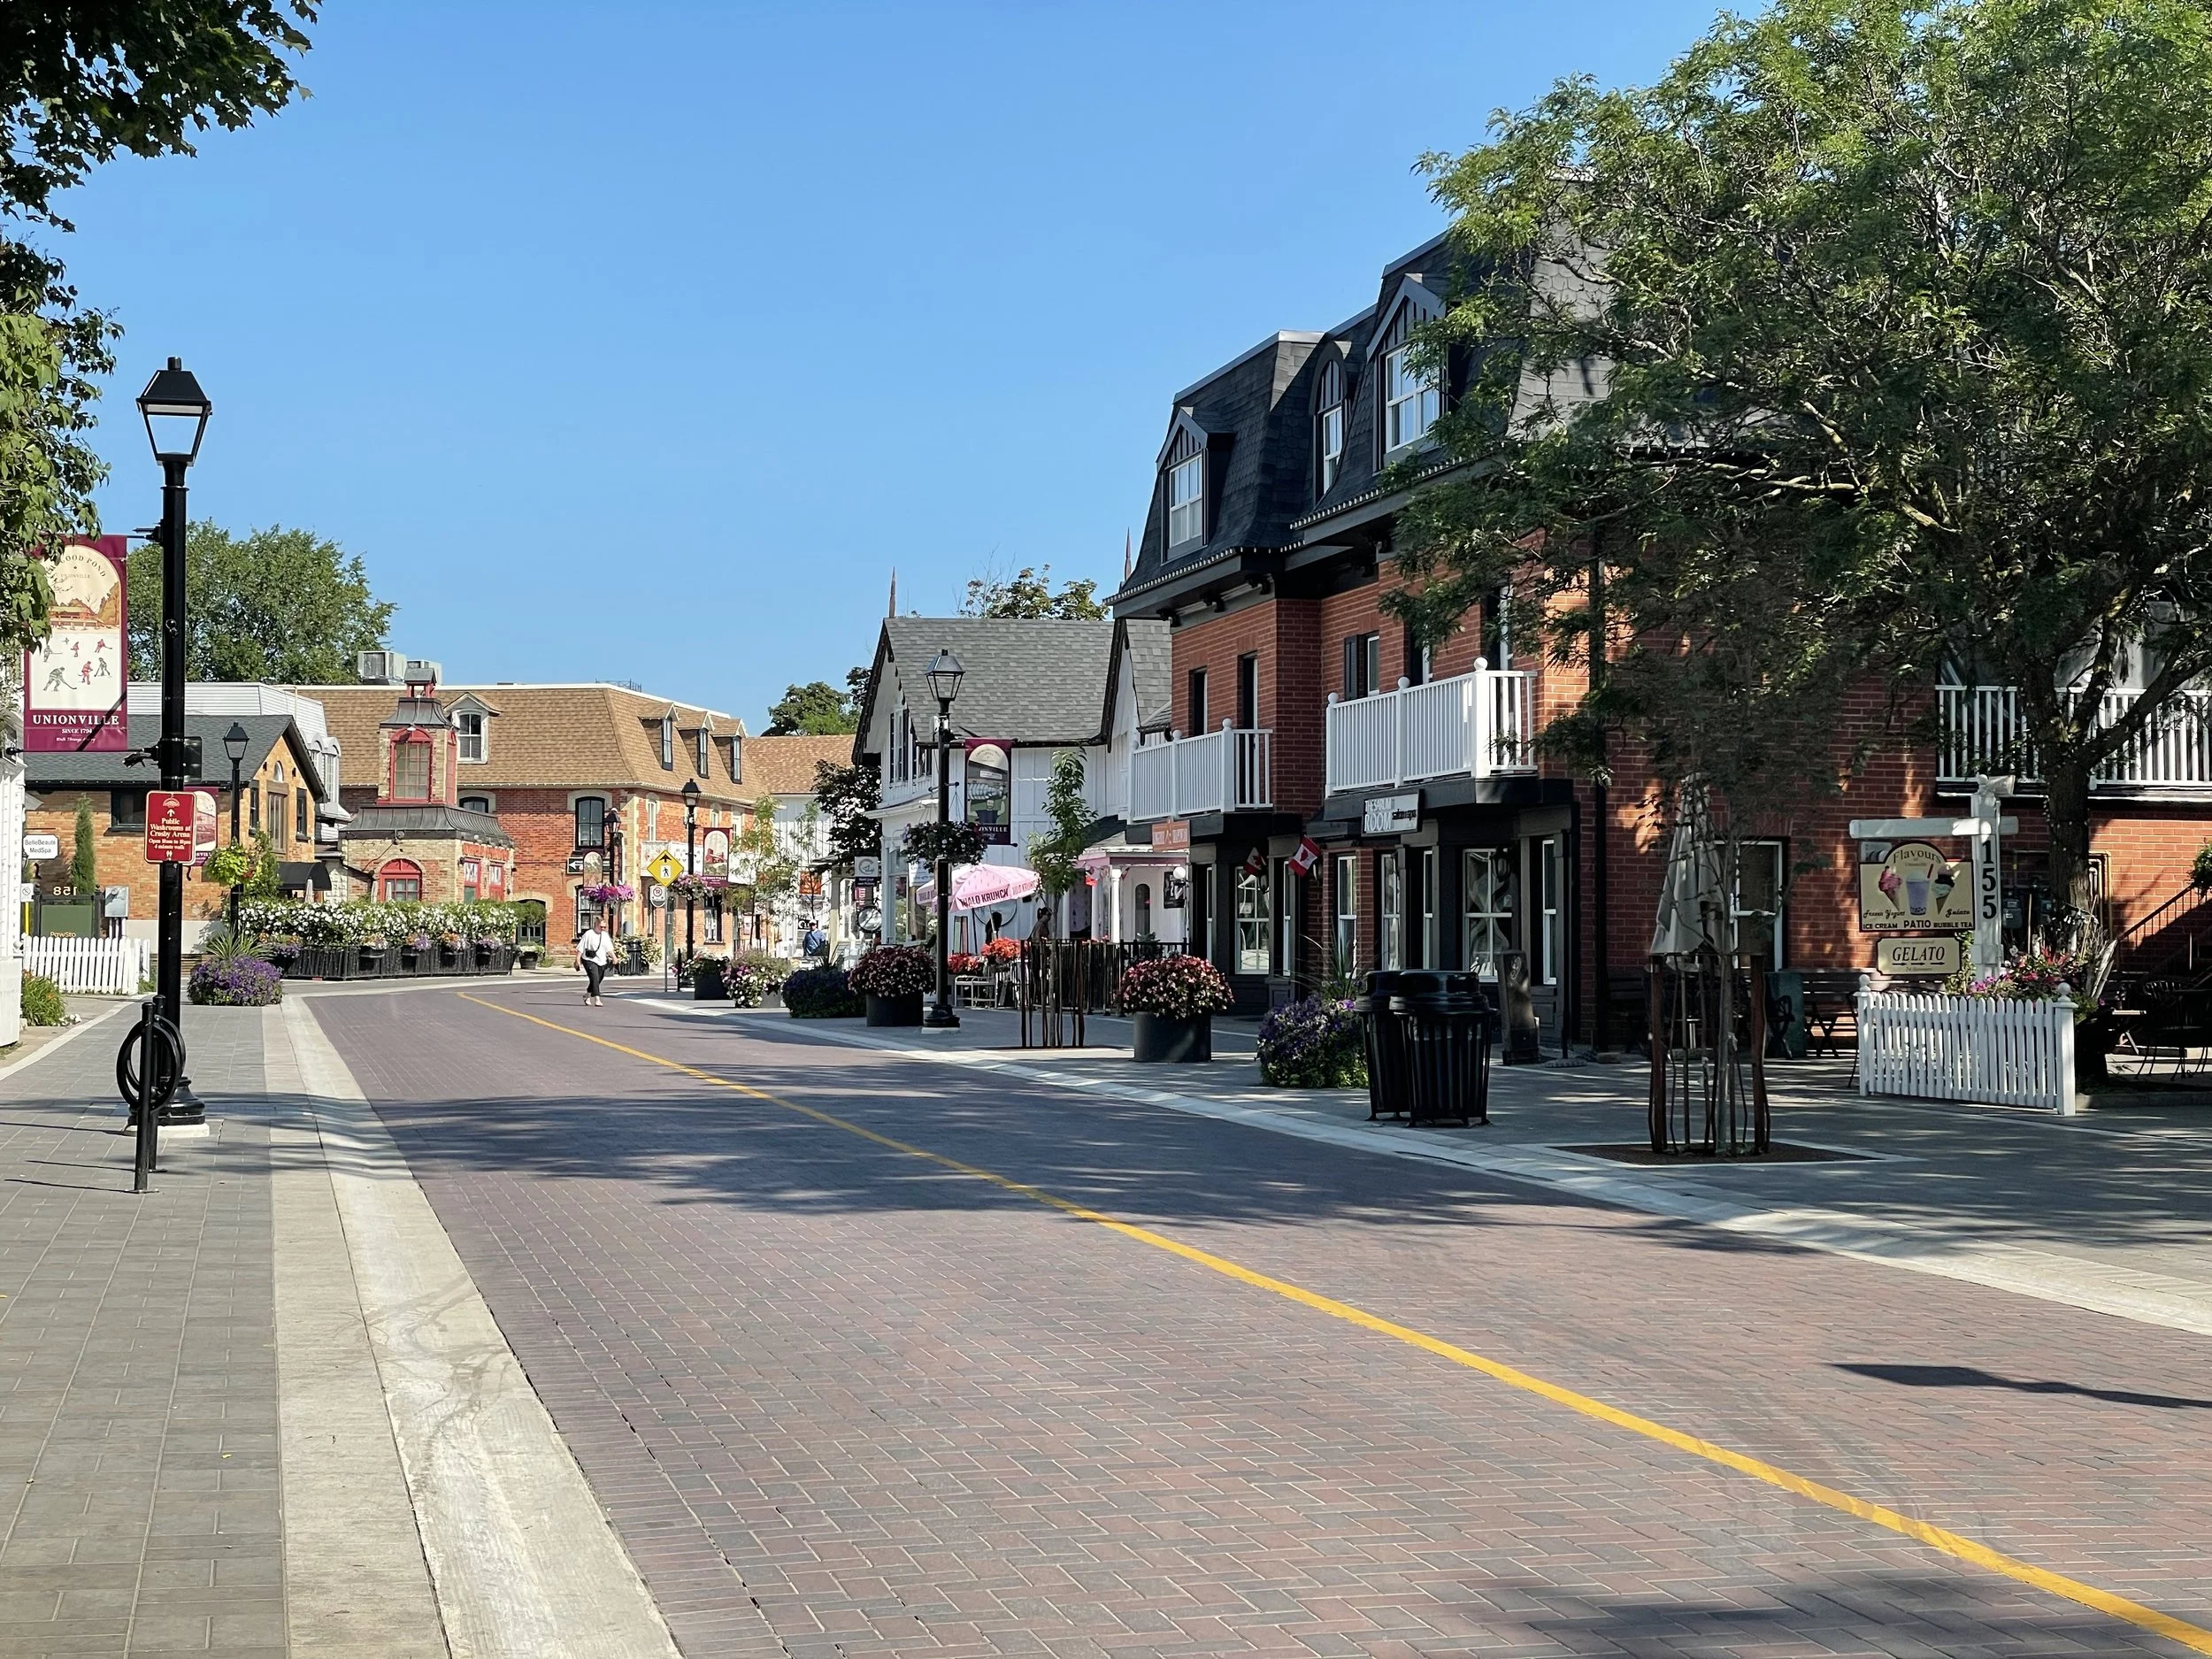
Main Street Unionville, July 2026

Main Street Unionville, July 2026