
If you own a condo, whether you live in it or rent it out, a recent Ontario court decision should change how you think about the plumbing behind your walls. Two Mississauga owners were held responsible for more than $42,000 in flood repairs, plus court costs, after a toilet in their tenanted unit overflowed, and the court did not need to find that they had been careless to reach that result (Bob Aaron, Toronto Star, September 21, 2026). Here is what happened, why the law works the way it does, and the handful of checks I would make this week if any of this sounds familiar.
What happened in the Mississauga unit
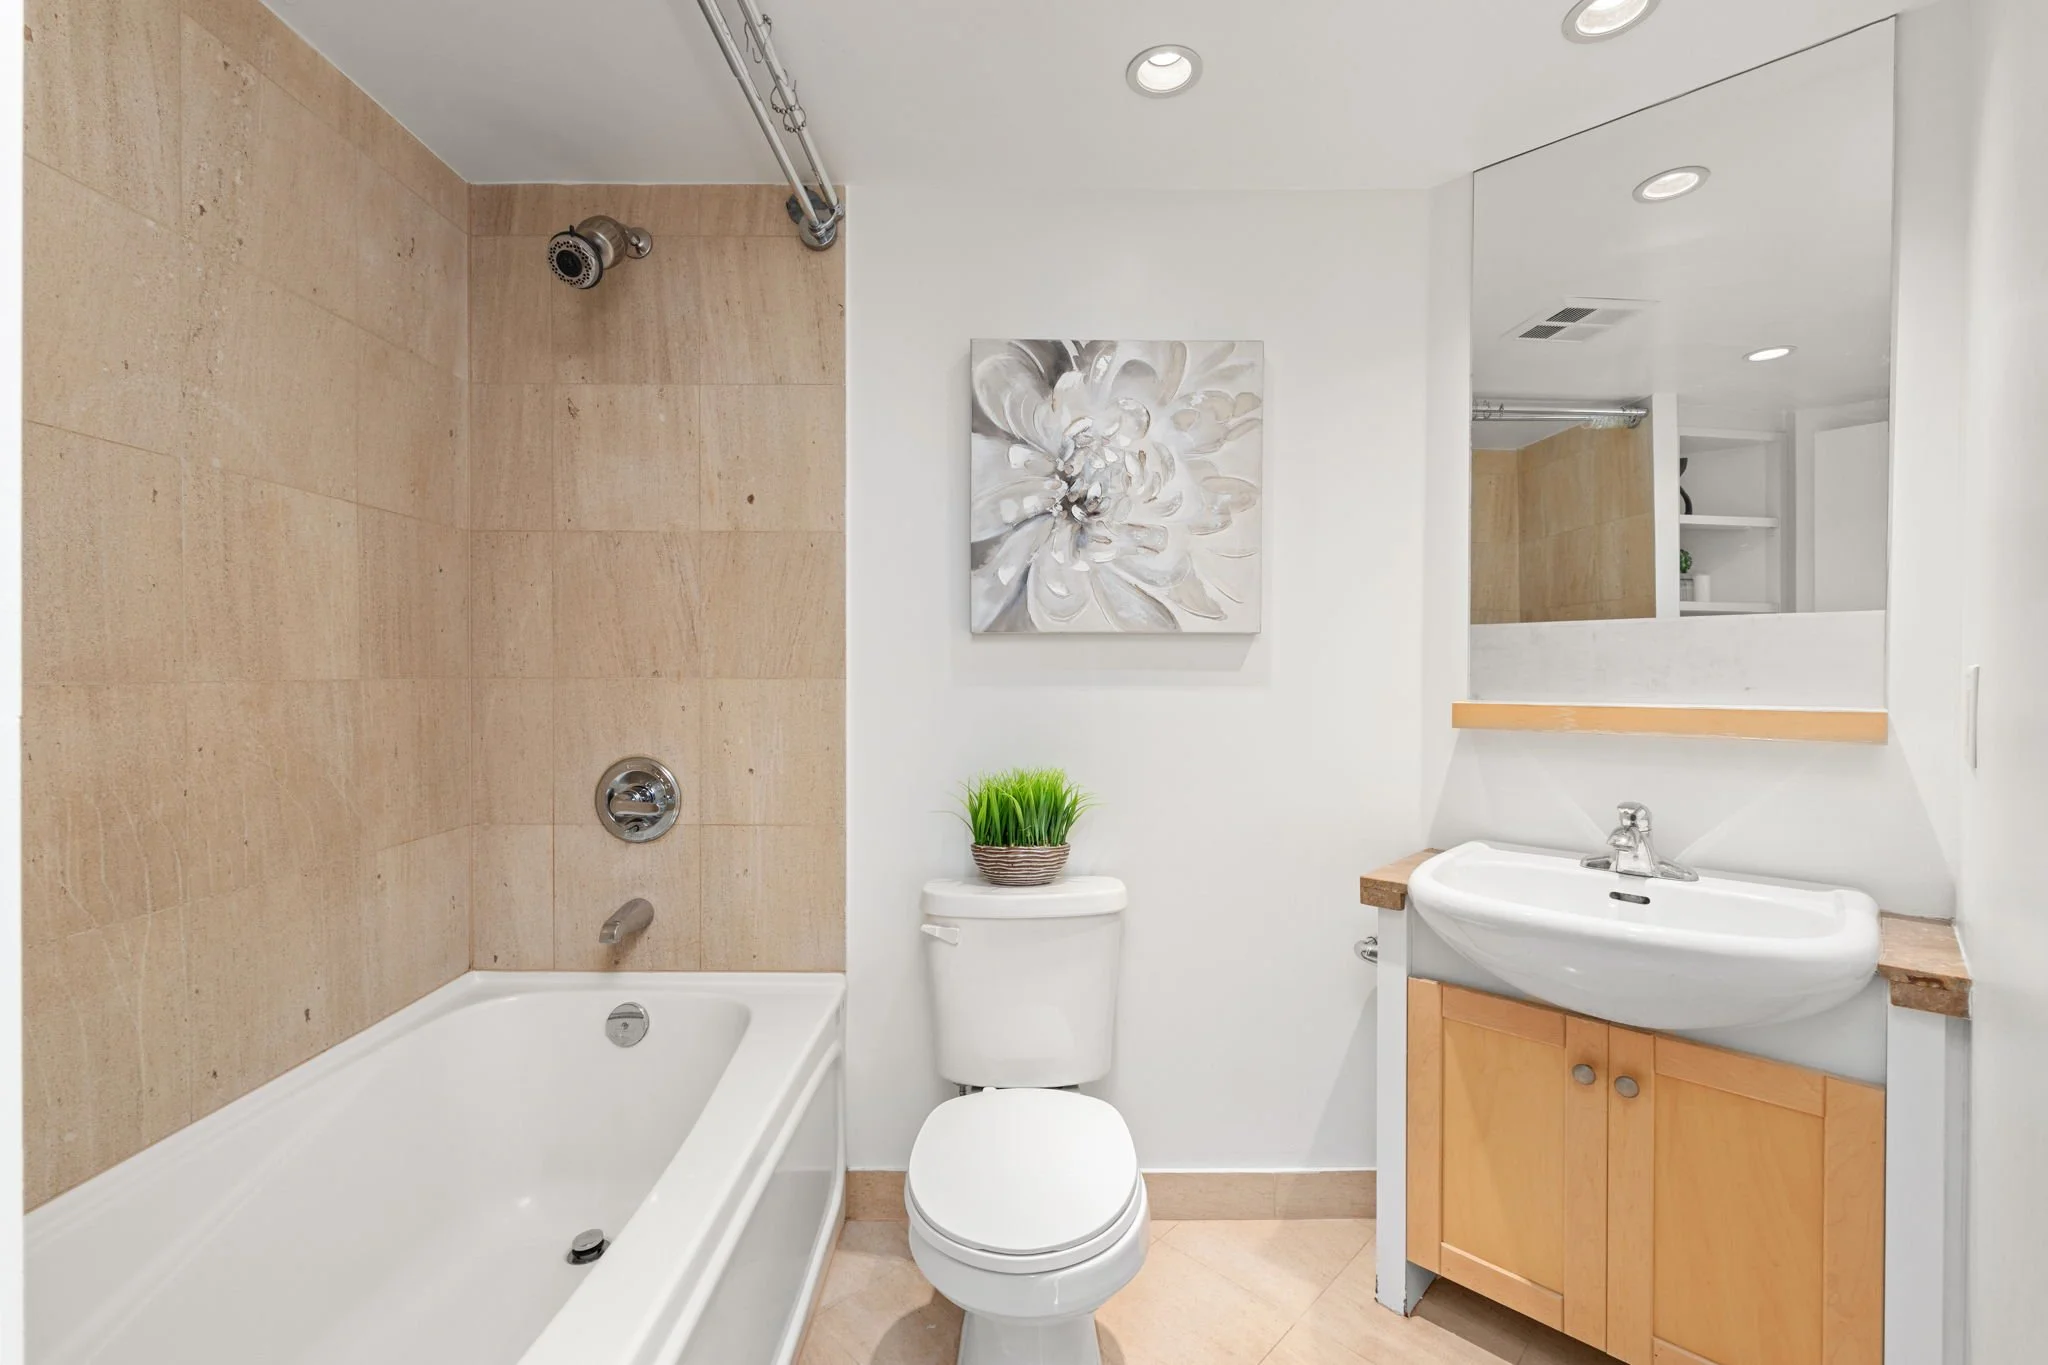
Toronto Condo Bathroom
Early one morning in January 2022, the toilet in a rented unit on Trailwood Drive overflowed and water ran into the suite below, several neighbouring suites and the common elements. When the superintendent arrived he found the flapper inside the tank sitting open, a blockage in the bowl, and a broken handle on the shut-off valve beside the toilet, which meant the tenants could not stop the water and he had to leave the suite to shut off the supply to the whole unit. Two contractors repaired the damage for a combined $42,233. The corporation's insurance deductible was $50,000, more than the entire loss, and its bylaw made an owner responsible for damage caused by an owner's or tenant's act or omission up to that deductible, so the corporation billed the owners for the full amount and, when they did not pay, registered a lien against the unit (Toronto Star, September 21, 2026, reporting the 2024 Ontario Superior Court decision of Justice Moiz Rahman).
Why careful owners can still be on the hook
The owners went to court to have the lien discharged, and the argument that matters to every condo owner in the province was this one: they said they had not been negligent, so they should not have to pay. The court disagreed. Following an earlier decision, Justice Rahman held that Ontario's Condominium Act does not require proof of negligence; the question is simply whether an act or omission by the owner or tenant caused the damage. Two facts settled it. Something had blocked the toilet, and the shut-off valve had not been maintained, so a problem that could have been stopped in seconds ran long enough to flood several suites. The owners were responsible for maintaining both. The lien stood, and on top of the $42,000 the owners were ordered to pay costs the column estimates at around $15,000, plus their own legal bill.
I want to be plain about what that means, because I hear the opposite assumption all the time from clients who own an investment unit. Being a responsible owner who lives elsewhere and has never had a complaint is not a defence. If a five-dollar part inside your unit fails and the damage spreads, the corporation's deductible is very likely coming to you, and deductibles of $25,000 to $50,000 or more are now common in newer towers, including the ones I see in Markham Centre and Unionville.
Four things to check this week
The first is the plumbing itself. Every toilet and sink in your unit has a shut-off valve, and most owners have never turned one. Turn each one, confirm it actually closes, and replace any that is stiff, corroded or broken, which is an inexpensive job for a plumber and, as this case shows, the difference between a mop and a lien. While you are at it, have the toilet flappers and supply lines looked at; braided steel supply lines are cheap insurance against the rubber ones that fail without warning.
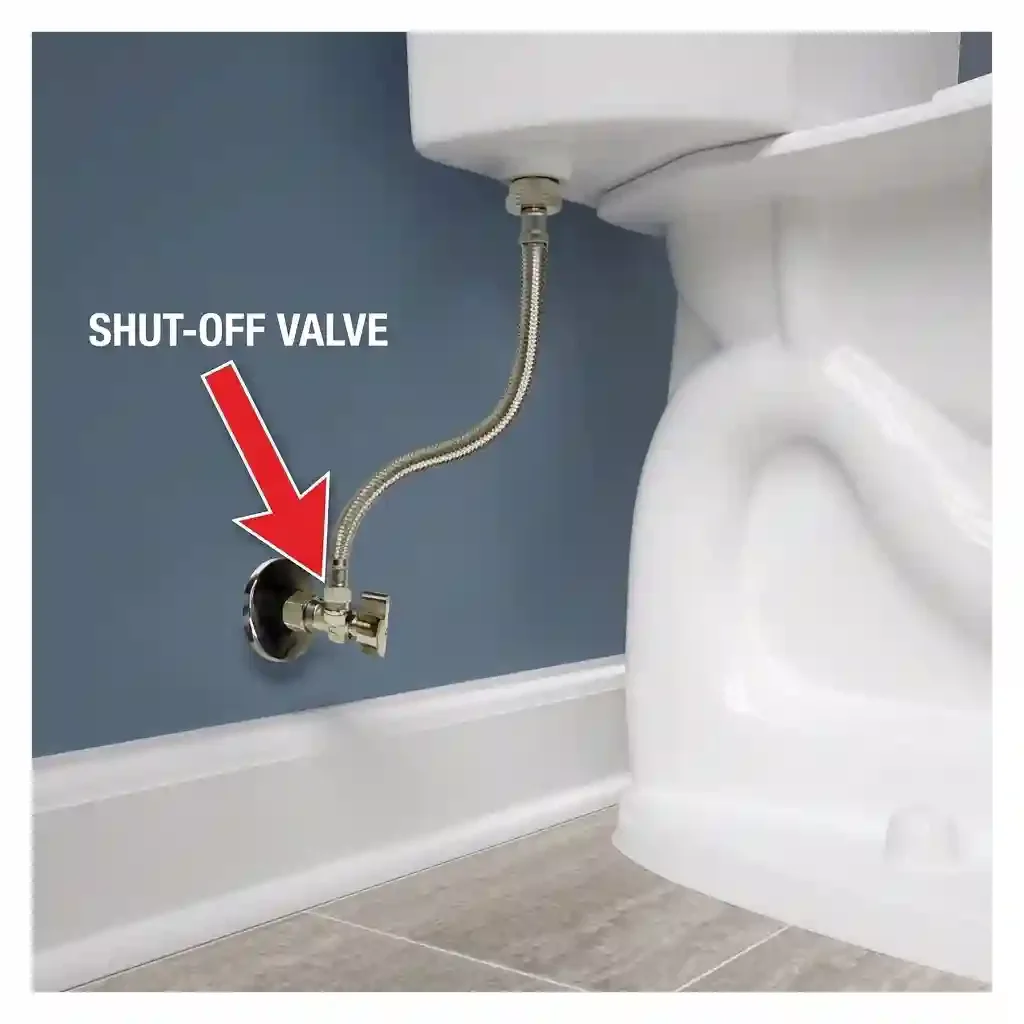
Typical Toilet Shut Off Valve
The second is your tenant, if you have one. Show them where the shut-offs are and how to use them, put it in writing, and keep a copy. The third is your own condo insurance. Ask your broker two questions: does the policy cover the corporation's deductible in a loss caused by you, your guests, your tenant or a tradesperson, and does it cover lost rent or living expenses if the unit is uninhabitable during repairs. Read the deductible coverage limit against the actual figure in your corporation's current certificate of insurance, because the limit that was fine when you bought may be well short of what the building now carries. The fourth, and the one I insist on for any client leasing out a unit: never hand over keys without a copy of the tenant's own insurance policy in your file.
None of this is complicated, and all of it can be done in an afternoon, which is exactly why it gets put off. A working shut-off valve, a tenant who knows where it is, and a policy that covers the building's deductible are what stand between a routine plumbing failure and a five-figure charge registered against your unit. If you own a condo and want a second opinion on what your corporation's deductible means for you, or you are weighing whether to keep the unit as a rental or sell it into this fall's market, call me and we will go through it.
Source The Toronto Star Sept 21 2026 Bob Aaron / CanLii