NEWS

Toronto Is Giving Away Fourplex and Sixplex Blueprints

Toronto spent a decade arguing about whether small apartment buildings belong on residential streets.  Now it is handing out the drawings.

The city has released a set of made-in-Toronto pre-approved designs for fourplexes and sixplexes, free for any property owner to download and use as the starting point for a building permit application.  The plans already meet the Ontario Building Code and Toronto's zoning rules, and they extend a catalogue the city began with its garden and laneway suite designs.  Maia Tustonic covered the launch in the Toronto Star on October 7.
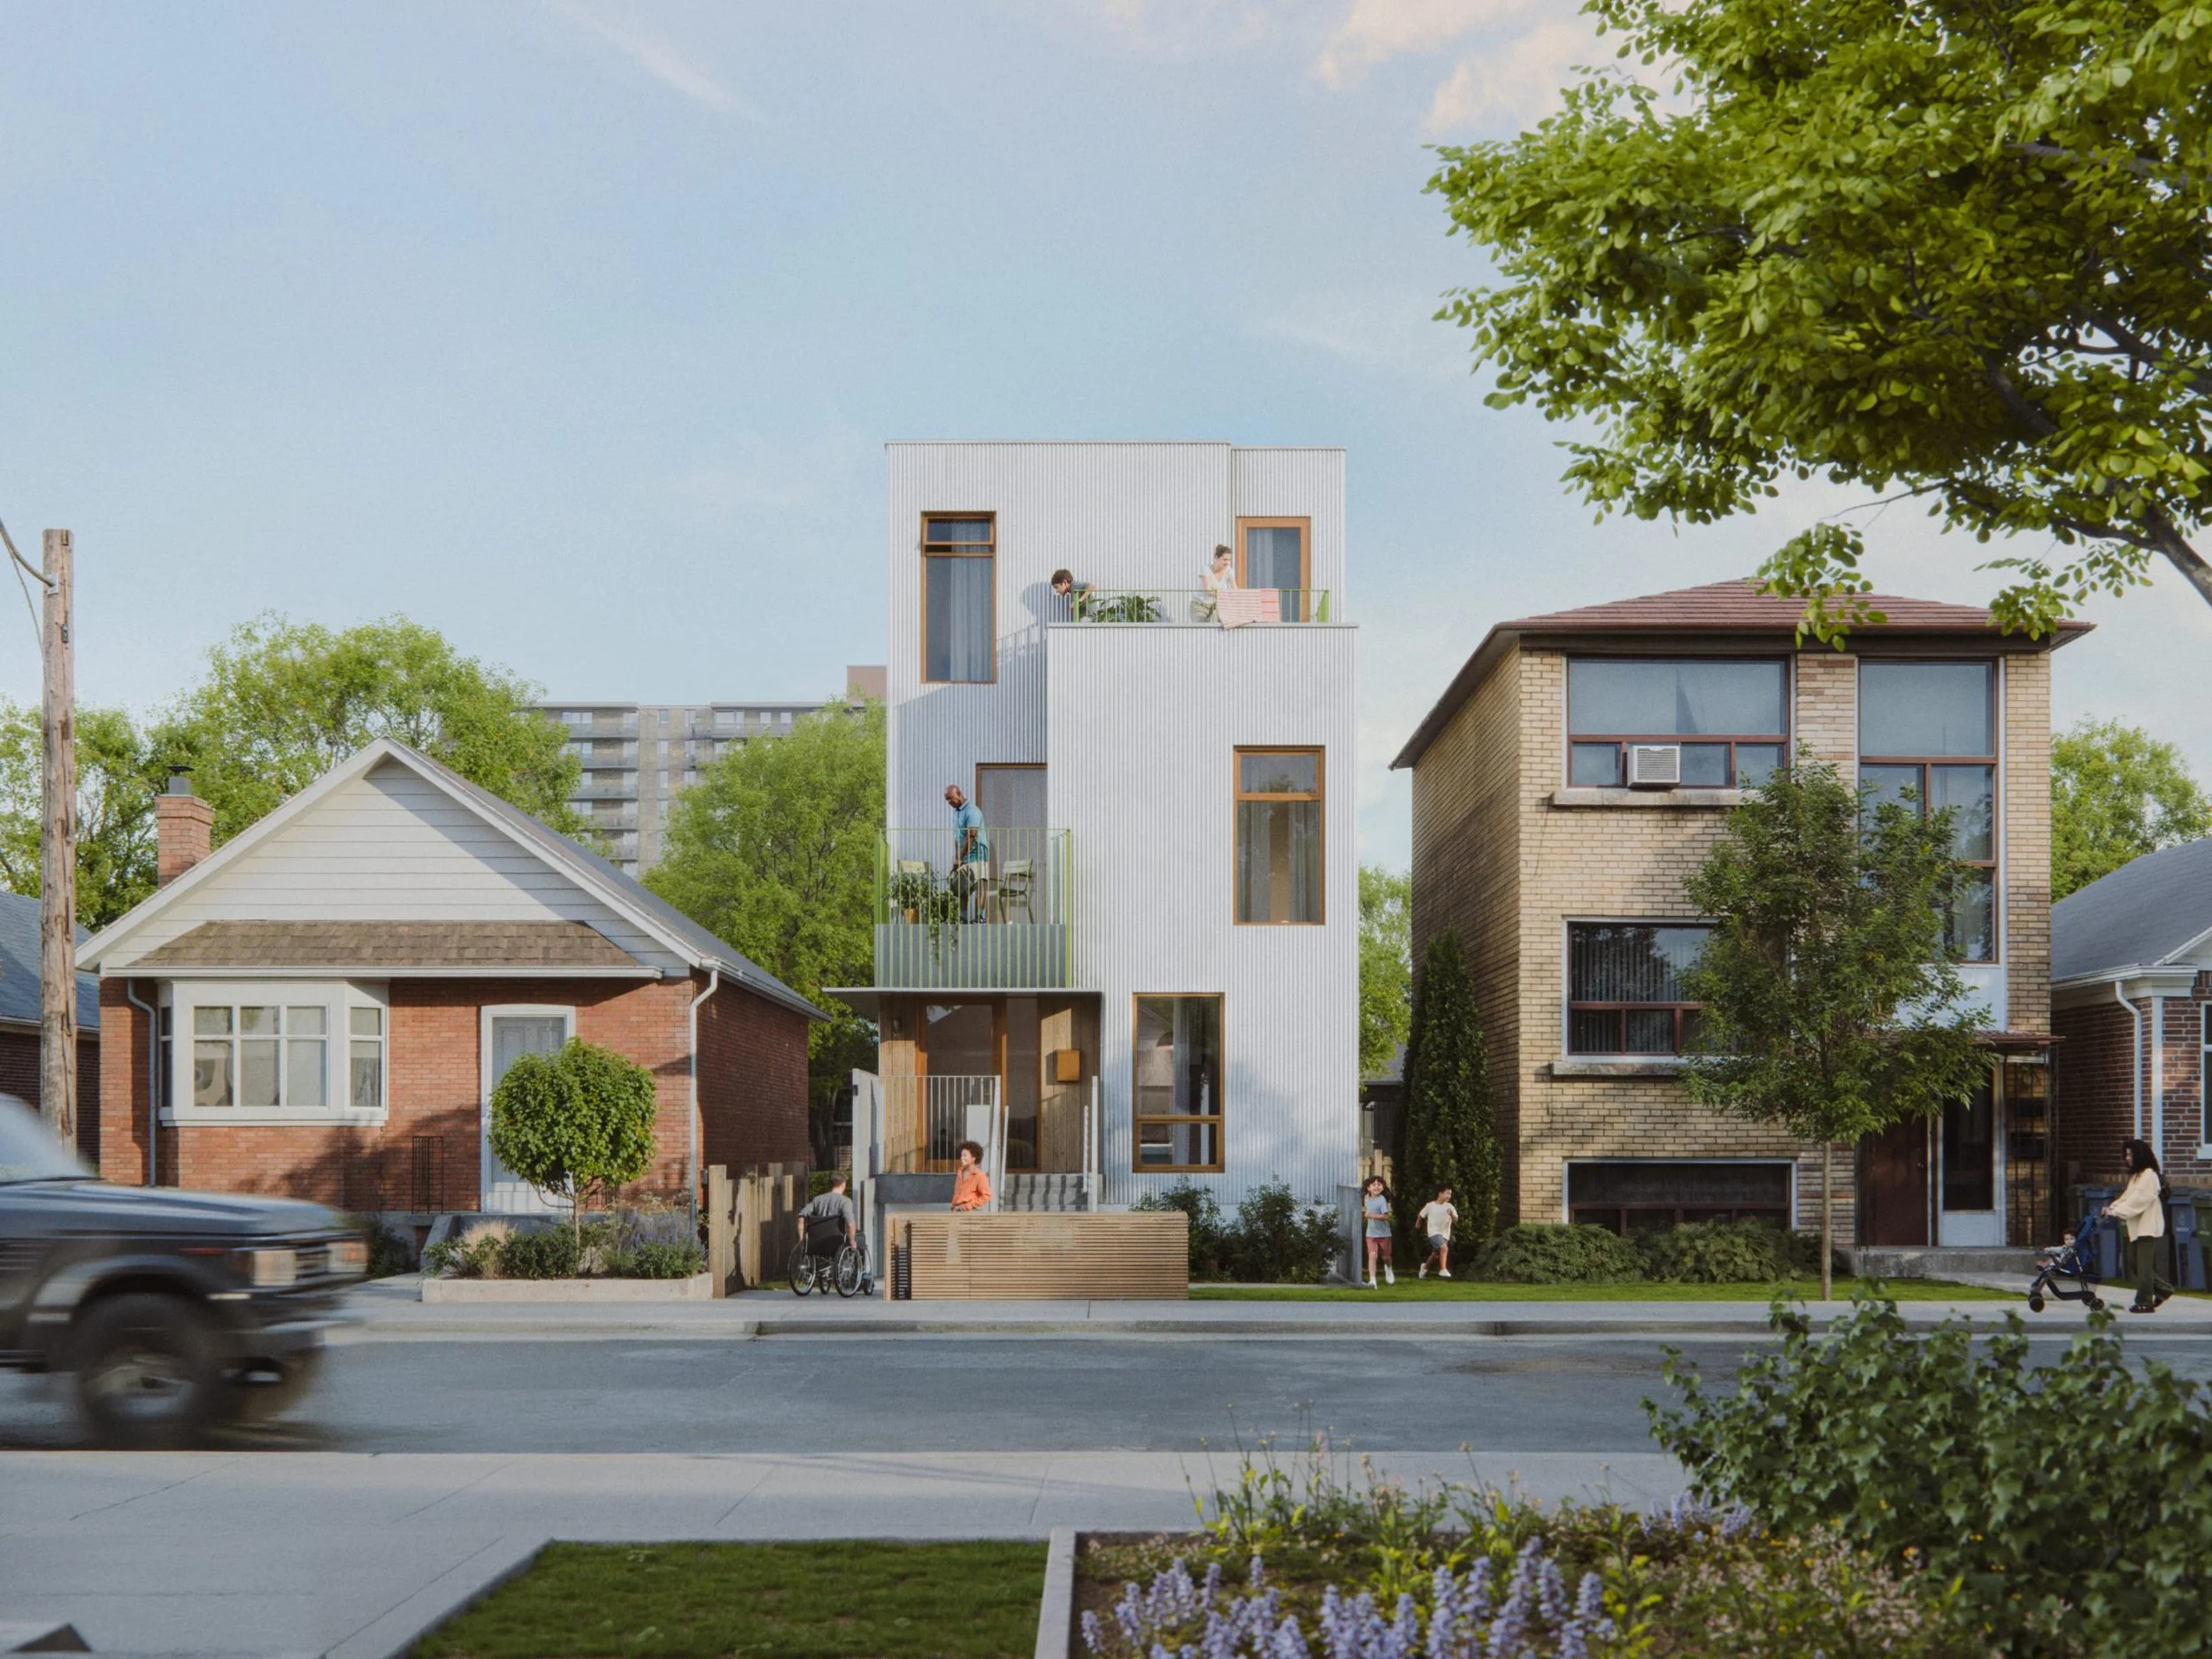
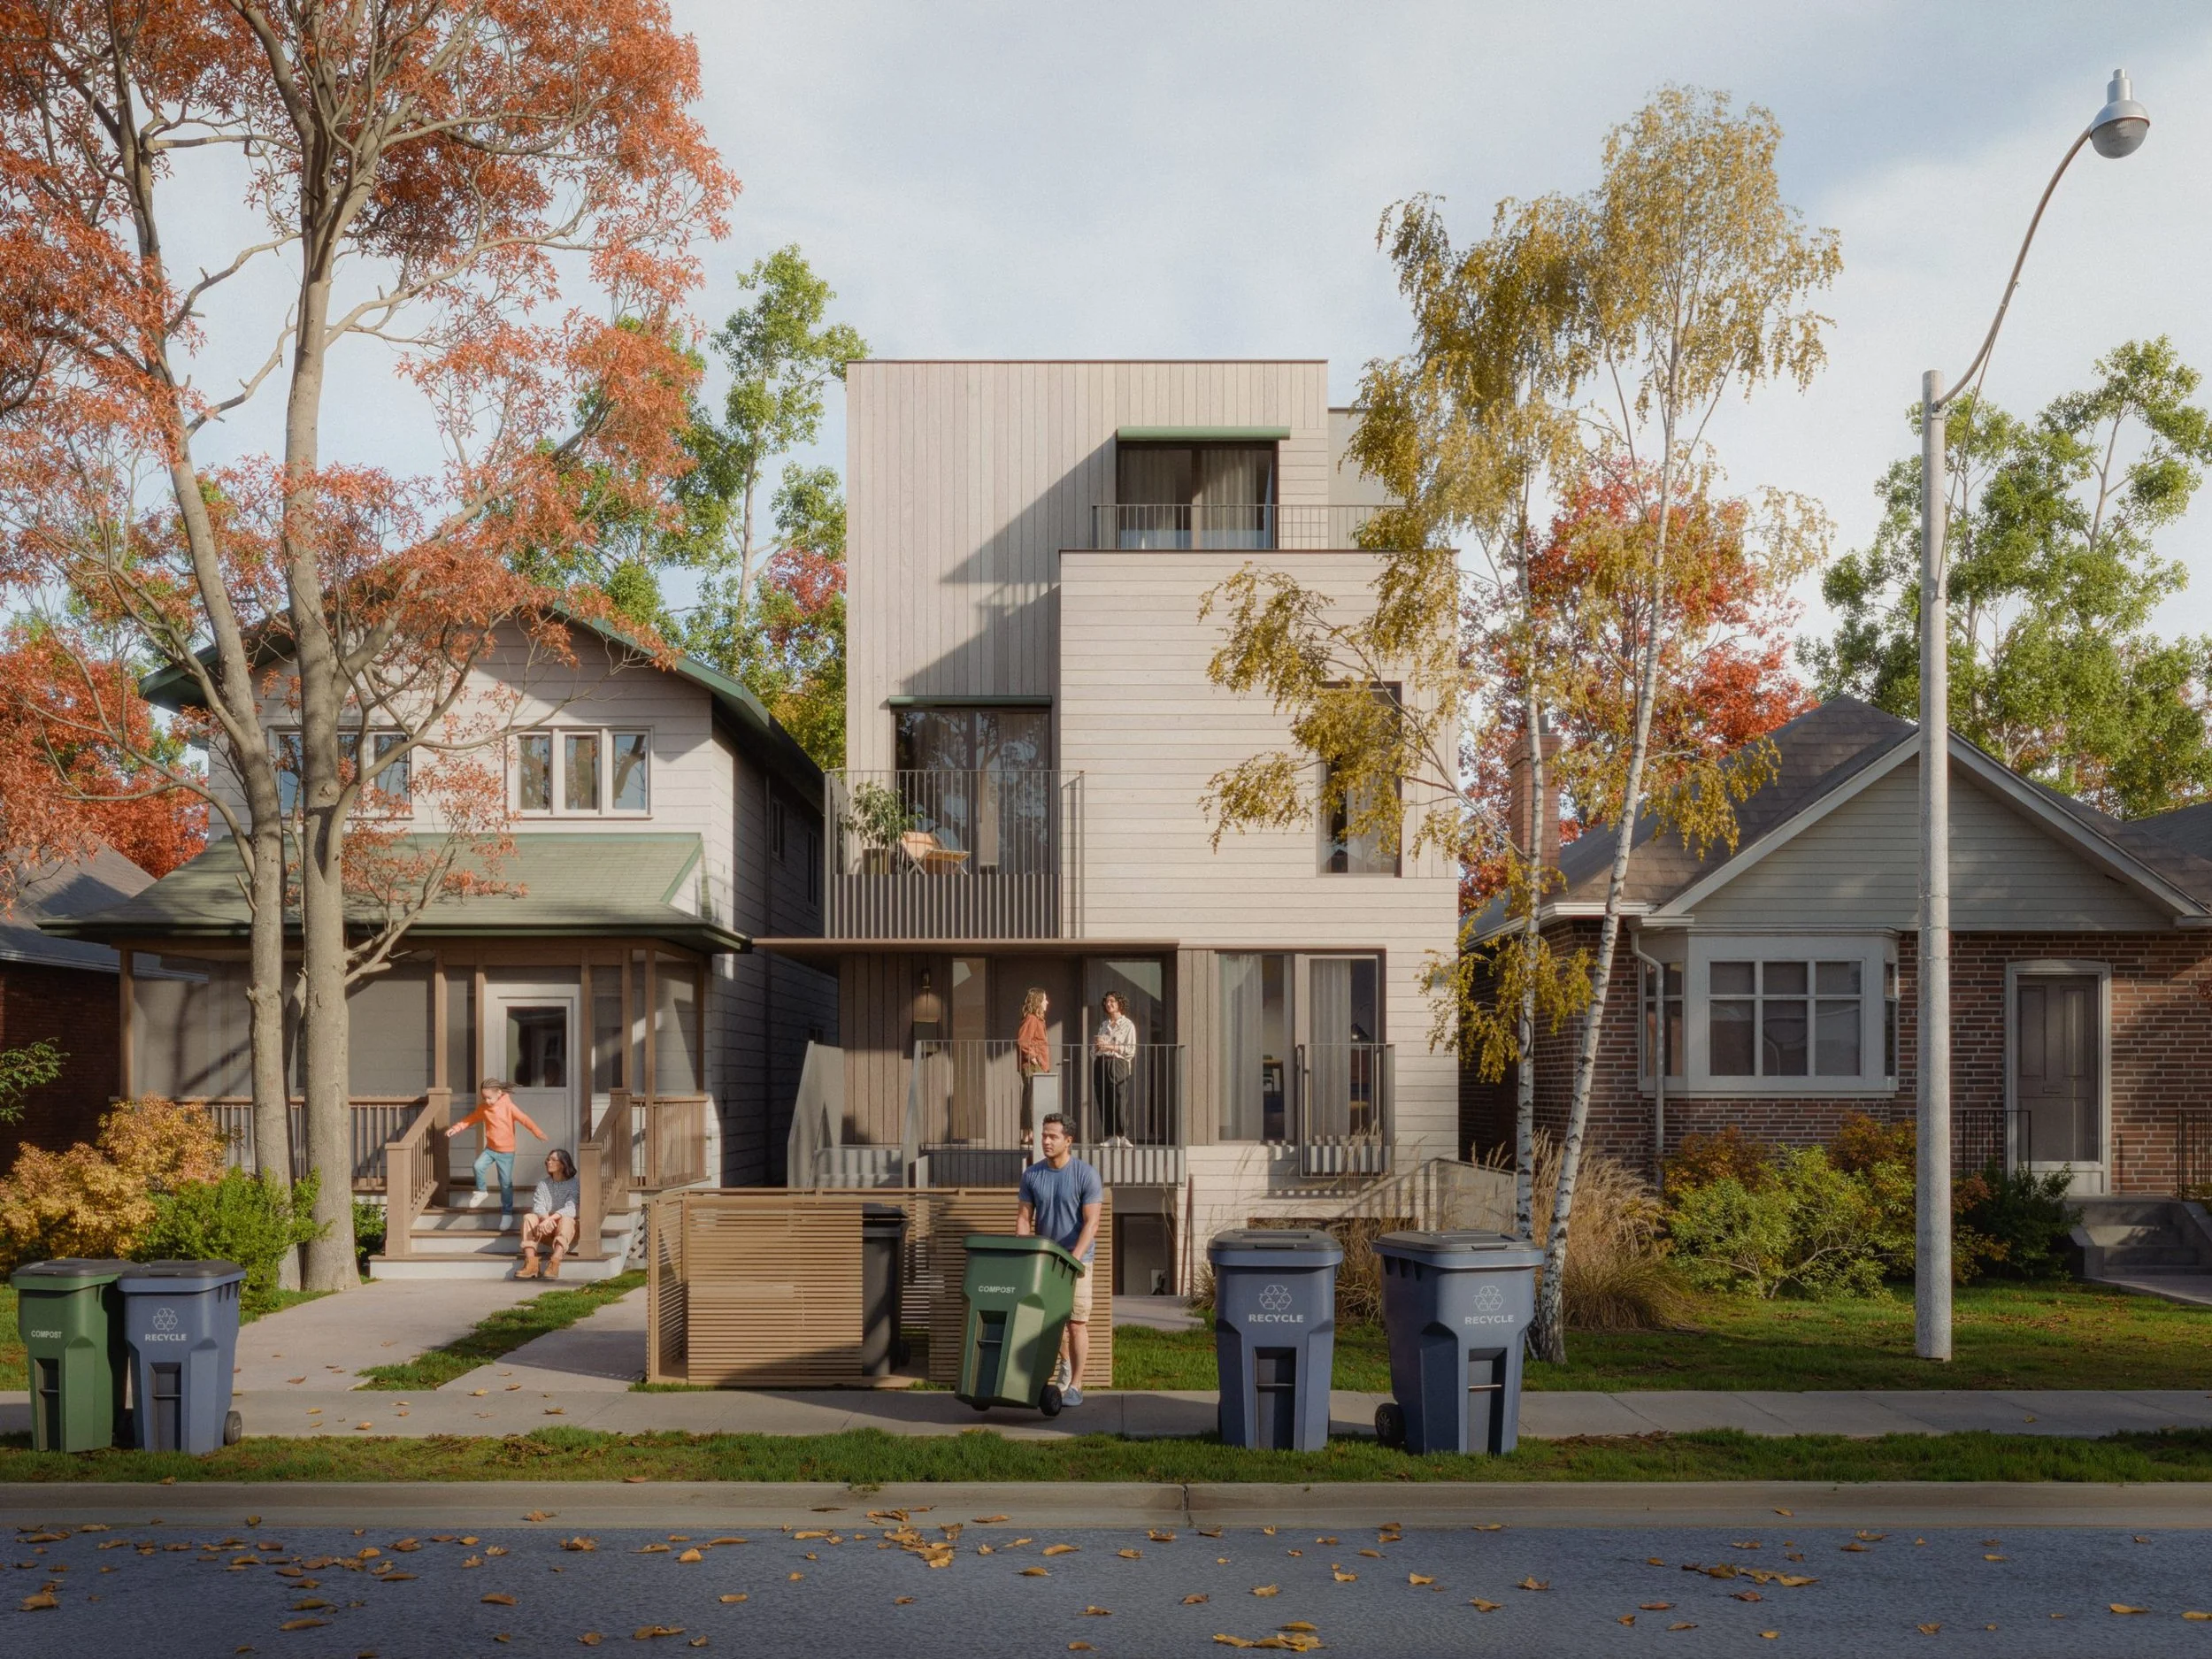
Toronto Fourplex Design Sample 1
Toronto Fourplex Design Sample 2

Some context for readers who have not followed this file closely.  Fourplexes have been legal on residential lots across Toronto since May 2023, and fiveplexes and sixplexes have been allowed in parts of the city without special permissions since last year.  What was missing was an affordable way to get from a legal right to a permit-ready drawing.  The new designs come in versions for narrow and wide lots, with options for bicycle parking, waste storage and features like heat pumps and solar, and builders can choose between brick and siding to manage the budget.  Kamal Gogna, the city's chief building official, says planning staff studied the most common Toronto lot sizes so the plans would fit real streets rather than ideal ones.  There is one catch worth underlining: a free plan is not a stamped drawing.  An owner still needs a qualified designer to adapt the design to their particular lot before the city will look at a permit application.

So what is the giveaway actually worth? Ron Sheinin of Modcity, a builder who does this work for a living, told the Star that designing a fourplex from scratch can run up to $60,000 in architectural fees and roughly another $20,000 for engineering, and the drawings alone take a month or two.  Start from a proven plan and a good chunk of that time and money comes back, which matters most to exactly the people this program is aimed at: the owner or small investor attempting a first multiplex, for whom the design stage is the most intimidating part of the project.

The skeptics have a point too.  Sean Galbraith, who runs an urban planning firm, argues that design fees were never what stopped multiplexes from being built; land and construction costs are the real wall, and they dwarf the architect's bill.  Toronto's lots also vary enormously in width, depth and grade, and a stock plan only helps if your lot happens to suit it.  "It's nice to have, but it's not going to move the needle much," he told the Star.

My own reading sits between the two.  Taking $80,000 of soft costs and two months of carrying time out of a small project is real money; on a tight pro forma it can be the difference between proceeding and passing.  But the more important thing here is the direction of travel.  Ten years ago, Canadian cities treated this housing form as something to be fought at committee.  Today the country's largest city is publishing the blueprints itself, and Ottawa put out its own catalogue of standardized home designs last year.  Governments have gone from permitting gentle density to actively packaging it, and I do not see that shift reversing.

These particular drawings stop at the Toronto border, but the thinking behind them does not.  Every Ontario municipality, Markham included, has had to allow up to three units on most residential lots since the province changed the rules in 2022, and the pressure to go further keeps building.  I notice it in a practical way: when I walk a wide lot in Markham Village or old Thornhill with a seller now, the conversation is as much about what the land could hold as about the house sitting on it.  Small builders are running that arithmetic quietly on ordinary streets, and on certain lots they are the strongest buyers in the field.

If you own a wide or deep lot on an older street, some part of your property's value now lives in what could be built there, and that part is growing.  Knowing that number before the sign goes up is the difference between pricing a house and pricing a property.  I have been doing more of this lot arithmetic this fall than ever, and if you suspect your property is one of these, it is a short conversation that can change the asking price.

Check out Toronto’s Multiplex plans for yourself here.


(Source: "City releases new fourplex, sixplex designs," Maia Tustonic, Toronto Star, October 7, 2026.)
GTA Home Sales Fell 9% in September, but Listings Fell Faster - and That Changes the Math

The September report from the Toronto Regional Real Estate Board is out, and the headline writers went straight for the sales number: 5,040 homes traded across the GTA last month, down nine per cent from a year ago. 

The Toronto Star framed it as economic uncertainty scaring off buyers and sellers, and that is true as far as it goes.  But the number that will do more to shape the next six months sits one line further down.  New listings dropped more than 14 per cent, to 16,500.  When supply falls faster than demand, a market tightens, and TRREB's Jason Mercer made the same point in the Star's coverage: the pullback on both sides has left the market somewhat tighter, even as it shrank.  A nine per cent sales decline and a tightening market sound like they cannot both be true.  In September, they were.

The rest of the report reads calmer than the headline.  The average selling price came in at $1.006 million, down about five per cent from last September and roughly 25 per cent below the February 2022 peak.  There were 26,131 active listings at month end, which works out to about four and a half months of inventory at the current pace of sales.  Homes sold for an average of 98 per cent of asking and took an average of 34 days to sell.  None of that describes a frozen market.  It describes a balanced one, populated by careful people.

What changed since the summer is worth understanding, because it explains where this goes next.  In August, sales were down only two per cent from a year earlier, and the talk was of shrinking supply setting up renewed competition among buyers.  Mercer's explanation for the sharper September drop is that the mood shifted: optimism about a trade deal faded as summer ended, inflation worries grew, and longer-term borrowing costs have risen with them.  I would add his own simpler point, which is that falling listings suppress sales all by themselves.  As he put it, "You can't buy what's not there." A buyer hunting for a particular kind of home on a particular handful of streets has fewer doors to knock on than a year ago, and some of September's missing sales are exactly that.

The softness is also unevenly distributed, and this is where I would slow down and read carefully.  Detached homes averaged $1.29 million, down about five per cent.  Condo apartments took the hardest hit, averaging just over $605,000, down about eight per cent, after two years in which completed projects and investor-owned units piled inventory onto that segment.  Townhouse sales fell about 13 per cent.  For a first-time buyer, the condo market now offers more negotiating room than I can recall seeing in a long while, in the very segment that is usually the entry point to ownership.

If you are thinking of selling, the practical reading of that 14 per cent drop in new listings is that much of your competition stayed home this fall.  A properly prepared home, priced to the last sixty to ninety days of truly comparable sales, is operating in a thinner field than it would have faced a year ago.  The discipline still matters, though: 98 per cent of asking and 34 days on market are the statistics of buyers who do their homework and quietly pass on wishful pricing.  That holds on a crescent in Unionville just as it does downtown.

For buyers, the arithmetic runs the other way.  TRREB continues to see substantial pent-up demand, households waiting for confidence in their jobs and in borrowing costs before they act.  Prices sit a quarter below the peak, selection is still reasonable at four and a half months, and sellers are meeting the market.  Mercer's caution is the one I would take seriously: if listings keep declining faster than sales, the choice buyers have been enjoying shrinks, competition returns in some neighbourhoods first, and the year-over-year price declines start to narrow heading into 2027.  The Bank of Canada's October 28 decision, which I wrote about here a couple of weeks ago, is the near-term swing factor, and a surprise in either direction will move psychology more than payment math.

Brad - Markham Realtor Sign

So the market in the headline is softer than the one in the report.  Sales fell because confidence wobbled and because inventory quietly thinned, prices gave back five per cent, and the segments pulled further apart.  If your plans for the next year touch either side of that market, the numbers behind the headline are worth twenty minutes of your time, and I am glad to go through them with you with your own street and your own house in the conversation instead of the GTA average.


(Source: Toronto Regional Real Estate Board September 2026 figures, as reported by Anastasia Blosser, Toronto Star, October 6, 2026.)

Inside Swan Lake Village, the Markham Community Where Downsizers Land

Every few months I find myself at a kitchen table in Unionville or Markham Village with clients in their late sixties, a pot of coffee going cold, and the same question hanging over the paperwork: if we sell this house, where would we even go? The four-bedroom served its purpose.  The garden has become a chore.  The stairs are a conversation.  And the answer, more often than people expect, turns out to be a place most Markham residents have driven past for years without ever seeing in: Swan Lake Village.

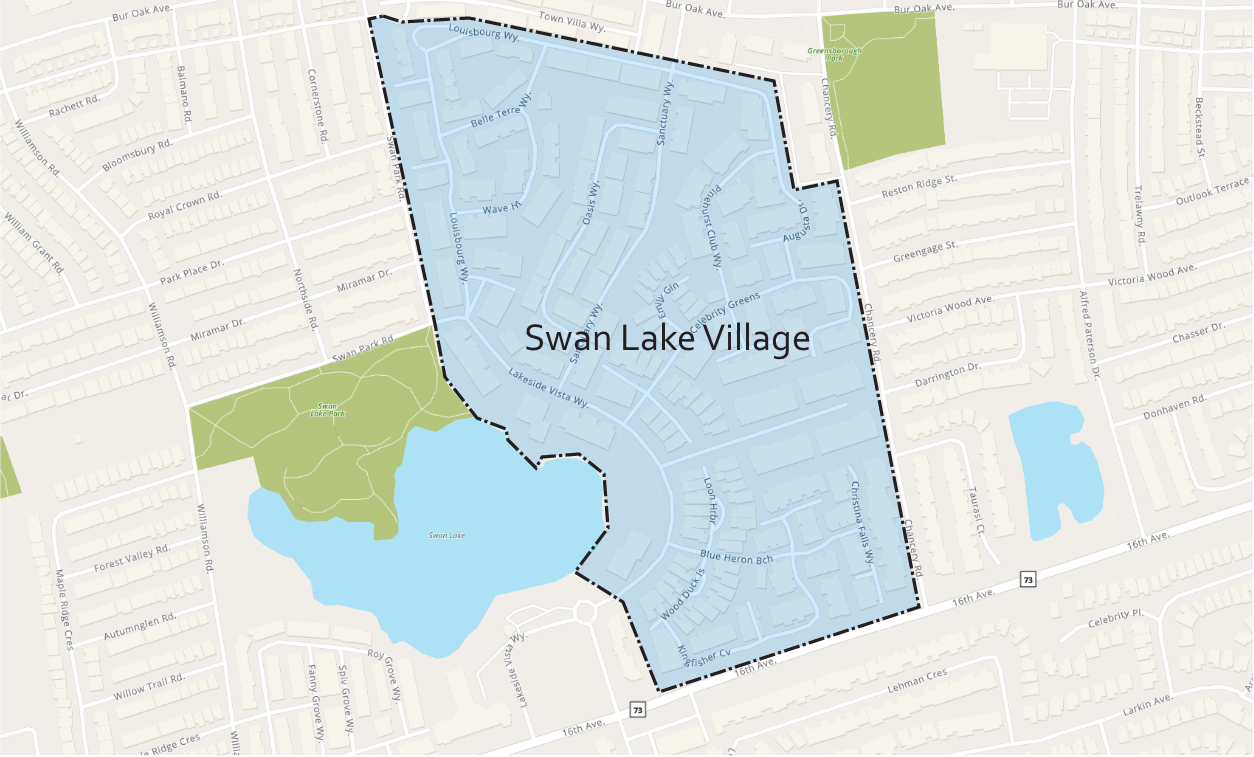
Swan Lake sits off Ninth Line at Sixteenth Avenue, wrapped around the kettle lake that gives it its name, and it is one of the very few gated communities anywhere in Markham.  The gatehouse is staffed around the clock.  Behind it are 649 homes, built in phases from 1997, when the first resident moved in on January 27 of that year, through to the final homes around 2010 (Swan Lake Village residents' site, swanlakevillage.ca).  It was designed from the first drawing as an adult-lifestyle community: homes are capped at two permanent occupants, pets are welcome within limits, and everything about the place, from the pace of the paths to the programming calendar, assumes the kids have moved out.

The variety inside the gates surprises people.  There are detached bungalows and bungalofts, two-storey townhomes, and four low-rise apartment buildings on The Boardwalk Way overlooking the water, with suites from about 1,100 to 2,000 square feet and some of the larger homes reaching 2,700.  That range matters, because downsizing is rarely one move.  I have known residents who went from a century home near Main Street to a bungaloft, and years later from the bungaloft to the Boardwalk, without leaving the gates or the friends they had made.

Those friends are the real product.  The Swan Club is a 16,000 square foot centre with an indoor pool, a gym, billiards and an art room; three satellite clubhouses add outdoor pools, tennis and pickleball; and the residents run more than thirty clubs of their own, from bridge to tai chi to line dancing (swanlakevillage.ca).  When I bring a hesitant client through, I do not start with a floor plan.  We walk the boardwalk, we poke our heads into whatever the art room is doing that afternoon, and somewhere on that walk the question quietly changes from why would we to which one.

Now the broker's portion, because this is still a real estate decision and the numbers deserve daylight.  Listings in Swan Lake currently run from the high $800,000s to about $1.7 million, with most homes trading between roughly $900,000 and $1.5 million (Oct 2026).  Selling a detached home in Unionville or Markham Village will usually fund the move with money left over, though less than people assume once land transfer tax, moving costs and any updating are counted.  Budget honestly for the monthly fees as well.  They cover water, cable and internet, building insurance, exterior maintenance, the gatehouse and the amenities, and residents who use what they pay for consider them money well spent - but they are a real monthly number, and I want clients to see it beside their retirement income before they fall in love with a sunroom.

I will also tell you who should not buy here, because that conversation saves grief later.  If your plan involves rental income, a grandchild staying for a school year, or a home office with staff coming and going, the rules will fight you.  And resale behaves differently inside a gate.  The pool of buyers is narrower than for a freehold bungalow on an ordinary street, so a well-priced home sells steadily to a motivated audience while an overpriced one can sit for months.  If it were my listing, I would price it tight to the last few sales of the same home style and let the community sell itself from there.

If the kitchen-table question in your house lately has been where would we even go, Swan Lake deserves an unhurried afternoon.  I am happy to walk it with you, floor plans in one hand and no particular agenda in the other.

New Home Sales in the GTA Tripled in August

Something happened in the new construction market this summer that deserves more attention than it got.  In August, 692 new single-family homes sold across the GTA.  A year earlier, that number was 215.  Sales have more than tripled from last year's historic low, and August came in 47 per cent above the ten-year average, according to figures prepared by Altus Group for BILD, the Building Industry and Land Development Association, and reported in the Toronto Star on September 22.

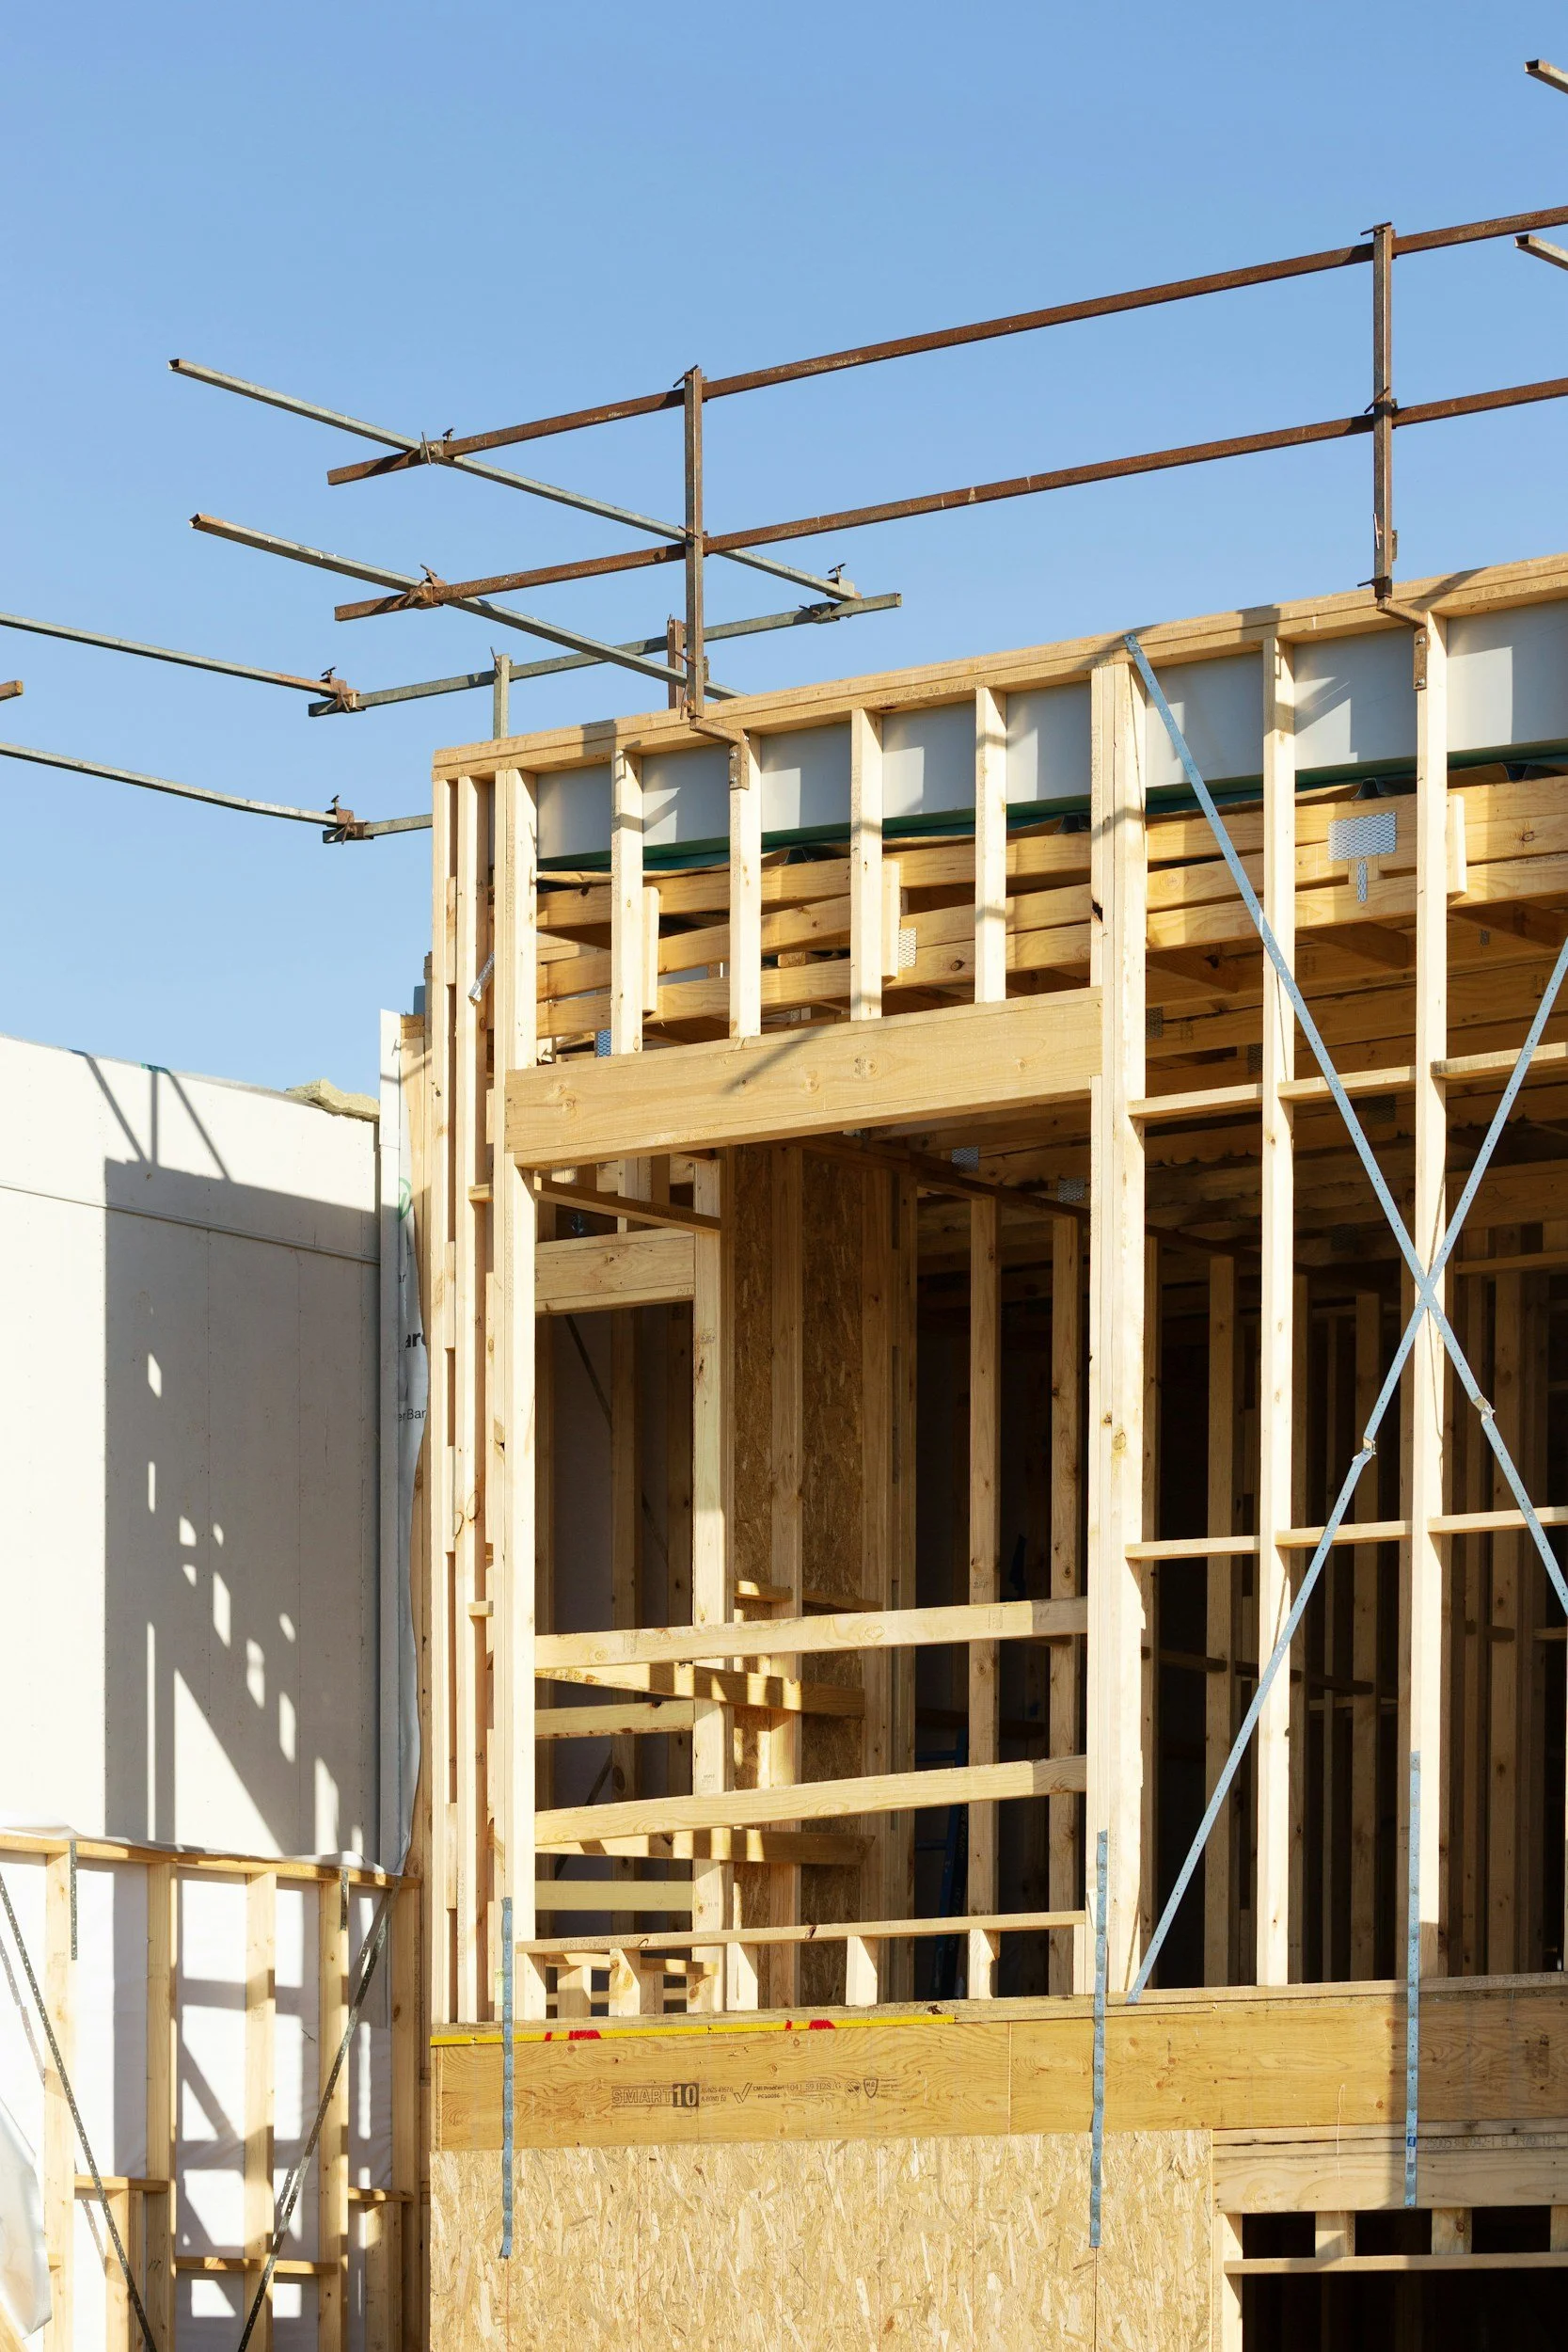
House Framing - New Construction

The HST Rebate Is the Reason

Numbers like that don't move on their own.  The push is coming from the HST rebate on new homes that the federal and provincial governments brought in this past April.  It's a one-year program, and it was designed as a lifeline for a building industry that had spent two years stuck between a backlog of unsold supply and a stubborn price gap between new homes and resale.  BILD reports five straight months of rising low-rise sales since the rebate arrived, and year-to-date single-family sales now sit at 5,550 - more than double last year's record low, and roughly in line with the ten-year average.

To understand why it's working, remember where new construction was sitting.  From the 2022 peak to the end of last year, new single-family prices had already fallen about 25 per cent, and even then almost nothing was moving.  The rebate closed enough of the remaining gap to get buyers signing again.  The benchmark price for a new single-family home was $1.25 million in August, down 14.6 per cent from a year earlier - and that's the gross price, before the rebate comes off.

Builders are responding in a particular way: townhomes.  Across the GTA, townhomes are taking a much larger share of single-family sales than the historical pattern would suggest, because builders are pricing them to make the most of the rebate.  We see it around here as well.  The townhome sites in Cornell and up through Victoria Square are exactly the kind of product this program was built to move.

Condos are a different story.  There were 215 new condo sales in the GTA in August.  That's double a year ago, but still 78 per cent below the ten-year average, and a long way from the 3,149 units that sold in August of 2021.  The rebate hasn't done much for condos because the program's rules around construction start and completion dates make it hard for most projects to qualify.  If you've been reading about trouble in the condo market, this is another chapter of the same book.

And before anyone declares a boom, one more number matters.  At the current pace of sales, it would take 38.5 months to clear everything builders have on the market.  A healthy market clears in nine to twelve.  Buyers still hold the stronger hand, and they will for a while yet.

So what do I take from all of this?  If you looked at new construction two or three years ago and walked away because the sticker made no sense next to resale, the arithmetic has changed.  Prices are down meaningfully from the peak, the rebate comes off the top, builders are motivated, and there is more finished and nearly finished inventory to choose from than I can remember seeing in a long time in this business.  The rebate runs for one year, which puts a quiet clock on the whole thing.

It matters on the selling side too.  Every sharply priced new townhome is competition for a resale one, and pricing a listing this fall without accounting for that is leaving the job half done.

If a new build has been somewhere in the back of your mind, this is a sensible season to look again.  Send me a note about any project you're curious about and we'll go through the real numbers together, rebate and all.

A Bank of Canada Rate Hike Is Now a Coin Flip - Here Is What to Do Before October 28

Three weeks ago the safe assumption was that the Bank of Canada would sit still until spring, and that assumption is gone.  On Wednesday the U.S. Federal Reserve raised its rate by a quarter point, its first increase in more than three years, and by Thursday the market was pricing the Bank of Canada's October 28 decision as a coin flip, with the odds tilted slightly toward a hike (CP24 and The Canadian Press, September 18, 2026).  If you have a variable-rate mortgage or a fixed term that renews in the next year, here is what that shift means for your monthly numbers and what I would do about it now.

How we got from a hold to a coin flip in three weeks

On September 2 the Bank held its policy rate at 2.25 per cent for the seventh straight decision, with the market putting the odds of a hold at 94 per cent going in (Bank of Canada; LSEG data cited by The Canadian Press).  Two things changed the picture.  The first is inflation: Statistics Canada reported on September 14 that the consumer price index rose 3.0 per cent in August from a year earlier, the same pace as July, with rent up 2.8 per cent and Ontario leading that increase (Statistics Canada, The Daily, September 14, 2026).  Three per cent is the top of the Bank's comfort range.

The second is what the Bank itself said.  In the summary of its September deliberations, released on September 16, the governing council wrote that if higher energy prices spilled over into other parts of the CPI, "it could require a monetary policy response to prevent broad-based inflation from setting in" (Bank of Canada, Summary of Governing Council Deliberations, September 16, 2026).  Oil is above US$100 a barrel because of the conflict in the Middle East, and as RBC's Claire Fan put it, if one thing is driving the pricing of the October meeting, it is oil.  Most economists still expect the Bank to wait until early 2027, but a hold is no longer the only scenario worth planning for.

If you are on a variable rate

Prime sits at 4.45 per cent and the best five-year variable rates are around 3.40 per cent (Ratehub, September 18, 2026), and a quarter-point hike moves both by the same amount.  On a $700,000 mortgage with a 25-year amortization, a variable rate of 3.40 per cent costs about $3,458 a month and 3.65 per cent costs about $3,551, a difference of roughly $93 a month; a second quarter point would take it to about $3,644.  Those are real dollars, but not the kind of jump that upends a household budget, whatever the headlines suggest.  The larger risk sits with anyone on a variable mortgage with a fixed payment, where the payment stays the same while more of it goes to interest and the amortization quietly stretches.  If that is your mortgage, ask your lender for your trigger rate and how much principal you are actually paying down each month.

If your mortgage renews in the next twelve months

This is the group I am most concerned about, and it has little to do with October.  Many of the mortgages taken out in the busy fall of 2021 renew this fall and through 2027, and those borrowers locked five-year fixed rates near 2 per cent.  A $700,000 mortgage taken at 2 per cent in the fall of 2021 carries a payment of about $2,964 and a balance today near $586,000, and renewed over the remaining 20 years at this week's best five-year fixed rate of 4.24 per cent, the payment becomes about $3,616, roughly $650 a month more.  CMHC reports that borrowers who renewed over the past eighteen months saw payments rise by an average of $375 a month (CMHC, cited by Money.ca, September 2026), and the 2021 cohort is starting from a lower rate than most of them did.

The big banks raised five-year fixed rates last week after the Canada five-year bond yield climbed to about 3.65 per cent, its highest since 2024 (Canadian Mortgage Trends, September 17 and 18, 2026), so if your renewal is within 120 days, get a written rate hold from your existing lender and at least one other today.  A hold costs nothing.  And do not sign the first renewal letter that arrives in the mail, because the rate printed on it is rarely the lender's best, and a broker who shops it can usually do better for a borrower with strong equity.

If you are buying or selling this fall

For buyers, lock a pre-approval with a rate hold and run your numbers at a half point above today's rate, so an October surprise does not change what you can afford.  For sellers, August showed inventory across the GTA tightening faster than sales, and more so here in Markham (TRREB Market Watch, August 2026), which still favours a well-priced listing, but October's buyers are carrying slightly higher borrowing costs than August's, so price to the last sixty days of sales rather than to the spring.

Whatever the Bank decides on October 28, the useful work happens before then: know your trigger rate if you are variable, get a rate hold if you renew or buy within four months, and shop the renewal rather than signing the letter.  A quarter point is manageable for almost every household I work with; being surprised by it is what causes trouble.  If you would like to run your own mortgage against these scenarios, call me and we will go through it together.

A $42,000 Toilet - Why Careful Condo Owners Can Still Be Handed the Building's Deductible

If you own a condo, whether you live in it or rent it out, a recent Ontario court decision should change how you think about the plumbing behind your walls.  Two Mississauga owners were held responsible for more than $42,000 in flood repairs, plus court costs, after a toilet in their tenanted unit overflowed, and the court did not need to find that they had been careless to reach that result (Bob Aaron, Toronto Star, September 21, 2026).  Here is what happened, why the law works the way it does, and the handful of checks I would make this week if any of this sounds familiar.

What happened in the Mississauga unit

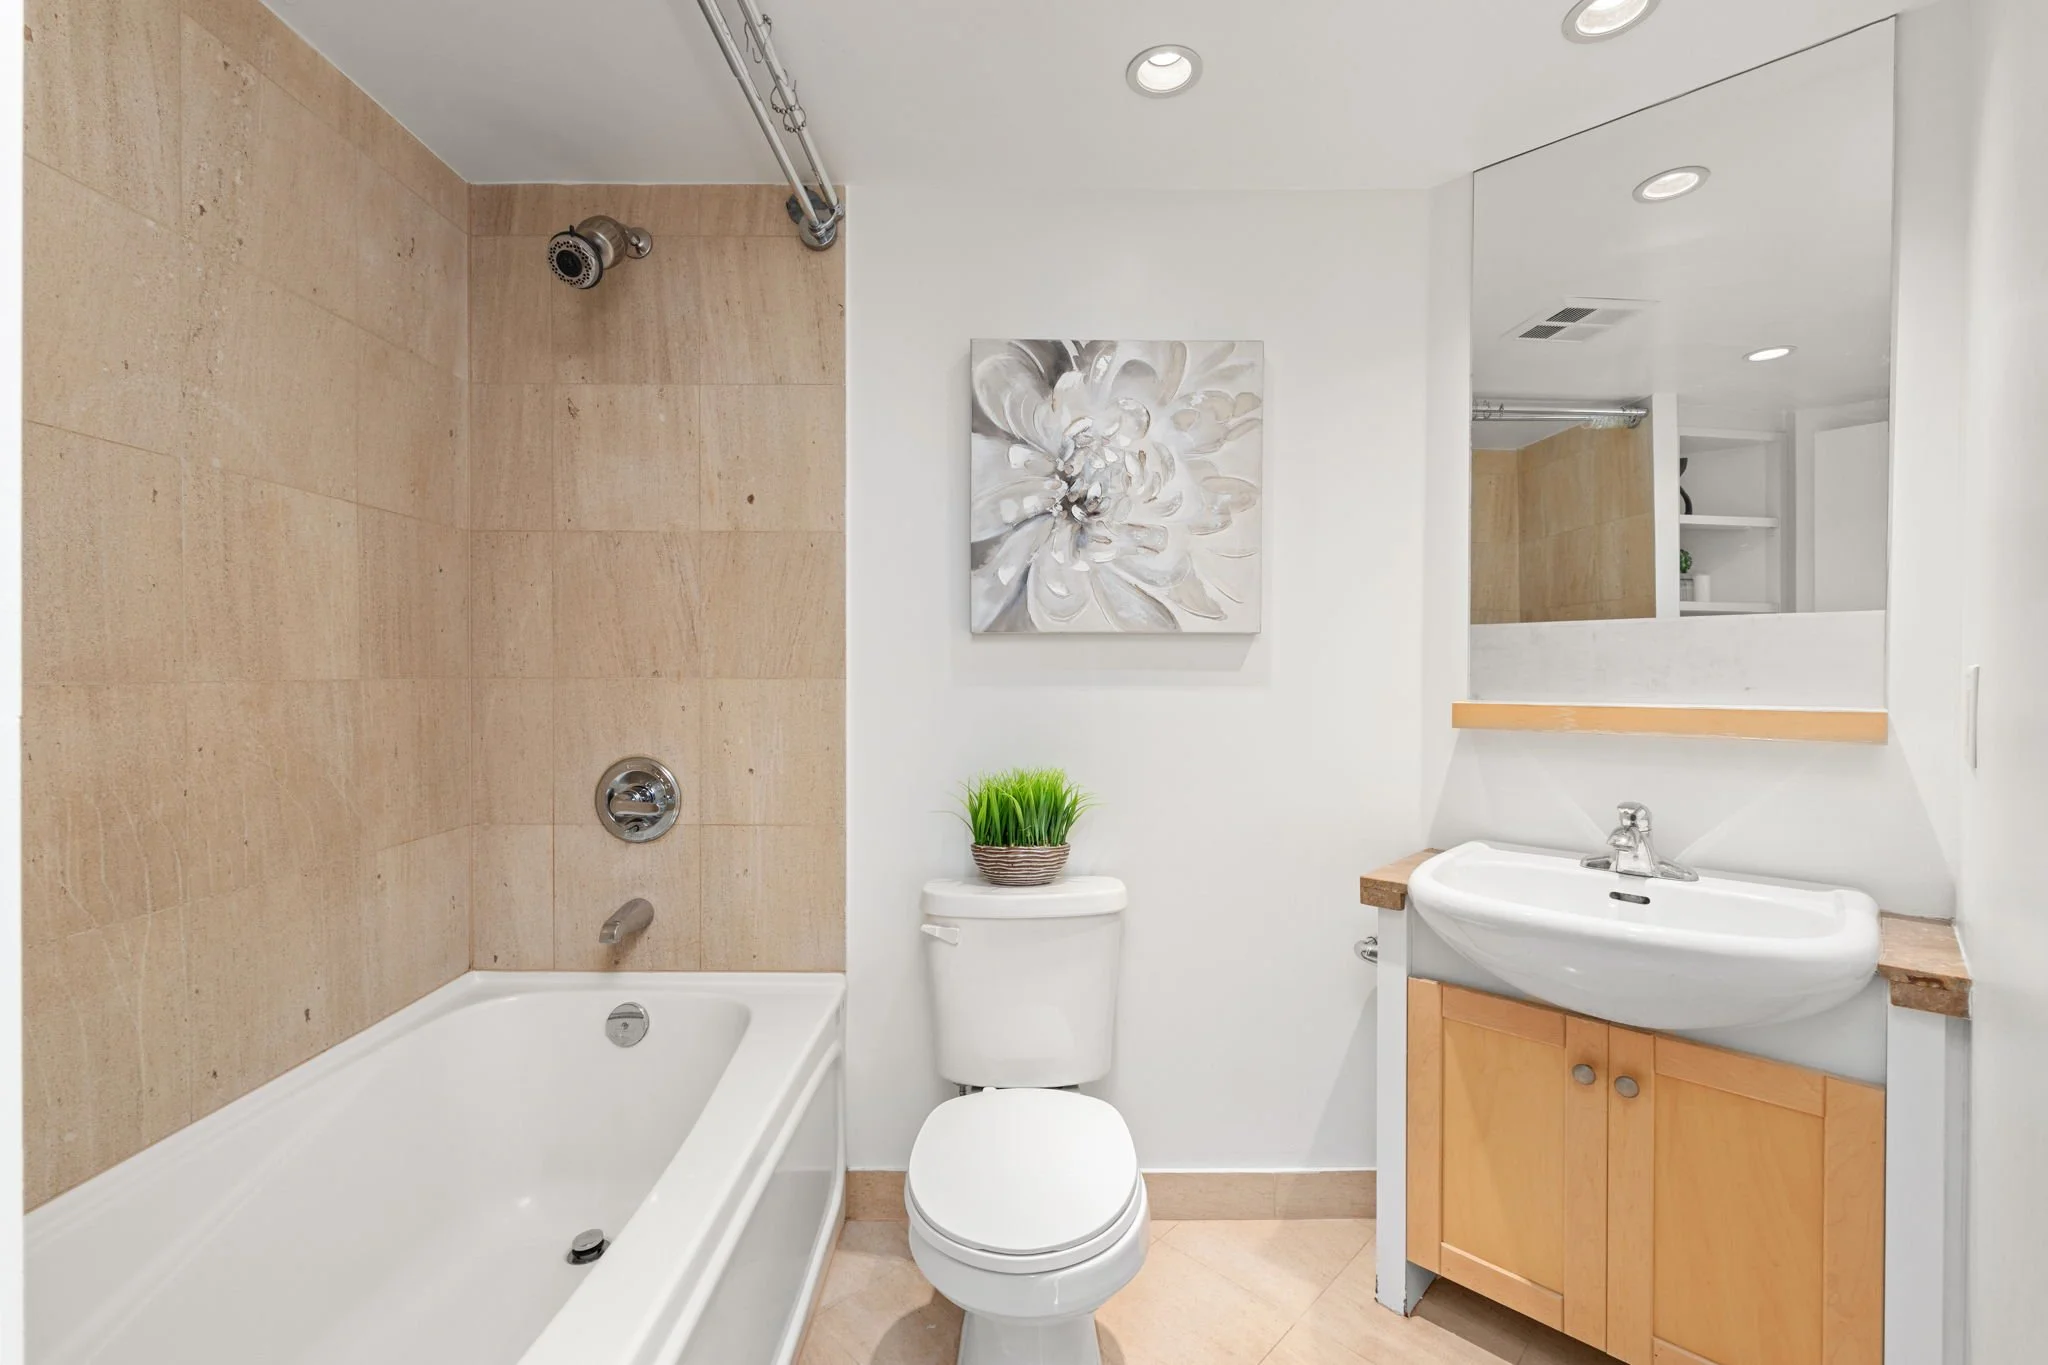
Small Condo Bathroom with Toilet

Toronto Condo Bathroom

Early one morning in January 2022, the toilet in a rented unit on Trailwood Drive overflowed and water ran into the suite below, several neighbouring suites and the common elements.  When the superintendent arrived he found the flapper inside the tank sitting open, a blockage in the bowl, and a broken handle on the shut-off valve beside the toilet, which meant the tenants could not stop the water and he had to leave the suite to shut off the supply to the whole unit.  Two contractors repaired the damage for a combined $42,233.  The corporation's insurance deductible was $50,000, more than the entire loss, and its bylaw made an owner responsible for damage caused by an owner's or tenant's act or omission up to that deductible, so the corporation billed the owners for the full amount and, when they did not pay, registered a lien against the unit (Toronto Star, September 21, 2026, reporting the 2024 Ontario Superior Court decision of Justice Moiz Rahman).

Why careful owners can still be on the hook

The owners went to court to have the lien discharged, and the argument that matters to every condo owner in the province was this one: they said they had not been negligent, so they should not have to pay.  The court disagreed.  Following an earlier decision, Justice Rahman held that Ontario's Condominium Act does not require proof of negligence; the question is simply whether an act or omission by the owner or tenant caused the damage.  Two facts settled it.  Something had blocked the toilet, and the shut-off valve had not been maintained, so a problem that could have been stopped in seconds ran long enough to flood several suites.  The owners were responsible for maintaining both.  The lien stood, and on top of the $42,000 the owners were ordered to pay costs the column estimates at around $15,000, plus their own legal bill.

I want to be plain about what that means, because I hear the opposite assumption all the time from clients who own an investment unit.  Being a responsible owner who lives elsewhere and has never had a complaint is not a defence.  If a five-dollar part inside your unit fails and the damage spreads, the corporation's deductible is very likely coming to you, and deductibles of $25,000 to $50,000 or more are now common in newer towers, including the ones I see in Markham Centre and Unionville.

Four things to check this week

The first is the plumbing itself.  Every toilet and sink in your unit has a shut-off valve, and most owners have never turned one.  Turn each one, confirm it actually closes, and replace any that is stiff, corroded or broken, which is an inexpensive job for a plumber and, as this case shows, the difference between a mop and a lien.  While you are at it, have the toilet flappers and supply lines looked at; braided steel supply lines are cheap insurance against the rubber ones that fail without warning.

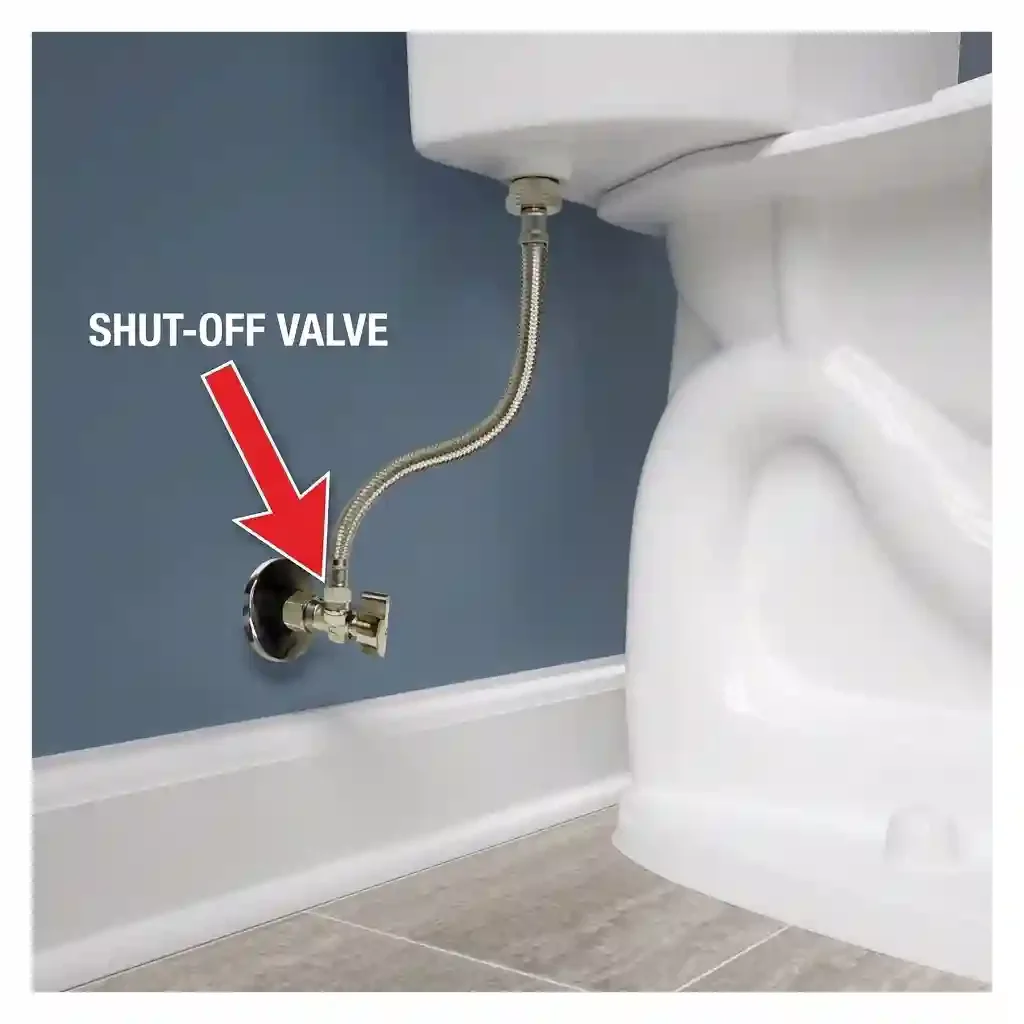
Toilet Shut-off valve placement

Typical Toilet Shut Off Valve

The second is your tenant, if you have one.  Show them where the shut-offs are and how to use them, put it in writing, and keep a copy.  The third is your own condo insurance.  Ask your broker two questions: does the policy cover the corporation's deductible in a loss caused by you, your guests, your tenant or a tradesperson, and does it cover lost rent or living expenses if the unit is uninhabitable during repairs.  Read the deductible coverage limit against the actual figure in your corporation's current certificate of insurance, because the limit that was fine when you bought may be well short of what the building now carries.  The fourth, and the one I insist on for any client leasing out a unit: never hand over keys without a copy of the tenant's own insurance policy in your file.

None of this is complicated, and all of it can be done in an afternoon, which is exactly why it gets put off.  A working shut-off valve, a tenant who knows where it is, and a policy that covers the building's deductible are what stand between a routine plumbing failure and a five-figure charge registered against your unit.  If you own a condo and want a second opinion on what your corporation's deductible means for you, or you are weighing whether to keep the unit as a rental or sell it into this fall's market, call me and we will go through it.

Source The Toronto Star Sept 21 2026 Bob Aaron / CanLii

Ontario's Rental Rules Change on September 21 - What Landlords and Sellers Need to Know

Unionville Rental Condo - Tridel

If you own a rental condo, a basement apartment or an investment townhouse anywhere in Markham, the rules that govern your relationship with your tenant change on Sunday, September 21.  The changes come from the second wave of Bill 60, the Fighting Delays, Building Faster Act, 2025, and they touch three things that come up constantly in my work: how quickly a landlord can act on unpaid rent, what happens at a hearing, and what it costs to reclaim a unit for your own family.  Here is what changes, and what I would do about it whether you are a landlord, a tenant, or someone buying or selling a home with a tenant in place.

The N4 window drops from 14 days to 7

The headline change is the notice for non-payment of rent.  Since the Residential Tenancies Act came into force, a landlord serving an N4 on a monthly tenant has had to give 14 days for the rent to be paid before an application could be filed with the Landlord and Tenant Board.  For any N4 served on or after September 21, that termination period becomes 7 days (Tribunals Ontario operational update, June 30, 2026; Bill 60, Royal Assent November 27, 2025).  Two details matter.  The 7-day period applies only to notices served on or after the 21st, and an N4 served before that date with a 7-day termination date is void, so if you are dealing with arrears right now, use the current form and the current 14 days.  And the notice is still only the first step; it opens the door to an L1 application, it does not end a tenancy on its own.

Persistent late payment gets a definition

Until now, "persistently late" was left to adjudicators to weigh case by case.  From September 21, the regulation defines it, and the working test is failing to pay rent within seven days of the due date on at least three occasions within a six-month period, subject to the conditions set out in the regulation (Ontario RTA amendments under Bill 60, effective September 21, 2026).  For a landlord in Markham whose tenant is chronically a week or two behind but always eventually pays, that is a meaningful change, because the pattern itself now has a legal name.  For tenants, it is a plain warning that paying on the 9th or 10th every month is no longer a harmless habit.

What changes at a hearing

Two procedural changes will matter more than they sound.  First, at a non-payment hearing, a tenant who wants to raise their own issues in response, such as maintenance complaints under section 82 of the Act, must first pay half of the arrears claimed, at least seven days before the hearing.  A tenant can still bring maintenance problems forward in a separate application, but the days of a repair dispute stalling an arrears hearing indefinitely are, in principle, over.  Second, and this is the change I want every downsizer and every parent with an adult child moving home to understand: when a landlord serves an N12 to reclaim a unit for their own use or a family member's use under section 48, the one month of compensation that has been mandatory is waived if the landlord gives at least 120 days' notice instead of the usual 60.  Give the tenant four months rather than two and the one-month payment falls away.

There is a wrinkle that matters if you are selling.  The waiver applies only to a landlord's own-use N12.  When a buyer purchases a tenanted property and needs the unit for themselves, that notice is served under section 49, and the one-month compensation still applies (Bill 60 implementation guidance, OntarioLandlord and PowerHouse Property Management summaries, 2026).  A seller who tells a buyer the tenant can be moved out for free is giving them the wrong information, and I would rather you hear that from me than at closing.

What I would do

If you are a landlord, update your forms and your calendar.  Use the new N4 only from September 21, keep a written record of every late payment from now on because the six-month clock on persistent lateness is now something you can prove, and if you have been thinking of taking a unit back for family, the 120-day route is worth the extra two months of patience.  If you are a tenant, pay on the day rent is due and keep your own records, because the margin for error has narrowed.  If you are buying or selling a tenanted condo in Markham, build the tenancy into the offer properly: the correct notice, the correct compensation, and a closing date that respects both.  I am not a lawyer and none of this replaces advice from one; for anything contested, a paralegal or lawyer who works at the Board every week is money well spent.

The rules governing Ontario rentals tighten on September 21, and the changes mostly favour landlords who keep good records and act correctly.  Update your forms, document your payments, and understand which N12 you are actually serving before you promise anyone a vacant unit. 


• Bill 60, Fighting Delays, Building Faster Act, 2025 (Royal Assent November 27, 2025): https://www.ola.org/en/legislative-business/bills/parliament-44/session-1/bill-60

• Tribunals Ontario operational update confirming the September 21, 2026 effective date (June 30, 2026): https://tribunalsontario.ca/ltb/

August 2026 TRREB Numbers: Markham's Fall Market Is Tighter Than It Looks

The August numbers from the Toronto Regional Real Estate Board came out last week, and the line most people saw was that the average GTA selling price slipped back under a million dollars.  That is true, and it is also the least useful number in the release.  The figure that actually tells you what this fall will feel like in Markham sits underneath it: new listings fell close to seven times faster than sales did, which means the wide selection buyers have enjoyed all year is quietly disappearing.

Fewer sellers, not fewer buyers

Across the GTA in August there were 5,057 sales, down 2.1 per cent from a year earlier, which is a modest dip and roughly what I would expect in a hot, quiet month when families are away.  New listings came in at 12,075, down 14.1 per cent, and active listings at the end of the month sat at 24,482, down 11.3 per cent from last August (Toronto Regional Real Estate Board, Market Watch, released September 3, 2026).  Read those three together and you get a market where sellers stepped back considerably harder than buyers did.

That is a meaningful turn.  For most of this year the leverage sat with buyers, and it sat there for one reason: they had options, and they knew it.  A buyer who could walk away from a house because three similar ones were sitting a few streets over was a buyer who could negotiate.  When the supply of comparable homes thins out, that leverage thins out with it, quietly and without any announcement.

What the Markham numbers say

York Region recorded 971 sales in August at an average price of $1,179,938, and within the region Markham averaged $1,208,692 (TRREB August 2026 community figures).  Prices are still softer than a year ago - the GTA average was down 2.7 per cent, and the MLS Home Price Index, which adjusts for the mix of what actually sold, was down 4.5 per cent - so I am not going to tell you values are climbing, because they are not.  What is changing is the competition, and competition is what sets the tone of a negotiation.  A detached home in Berczy or Wismer listed in October will have fewer comparable homes sitting beside it than the same house would have had in May, and that difference shows up in how confident a buyer feels about pushing on price.

If you are selling this fall

The first thing I would do is price to the last sixty days rather than to the spring, because with the index down 4.5 per cent year over year, a comparable sale from April is telling you a story that has already ended.  The second is to take presentation seriously.  Homes across the GTA took an average of 35 days to sell in August, and in a market with a modest buyer pool, the listing that photographs well and shows well is the one that gets the early attention while the others wait.  Thinner inventory helps you, but it does not rescue an optimistic price.  It simply means an honestly priced home now has a better chance of being the obvious choice rather than one of six.

If you are buying

The instinct right now is to wait, on the theory that more homes and better prices are coming.  I would be careful with that.  The Bank of Canada held its policy rate at 2.25 per cent on September 2, so borrowing costs are steady for the moment, and steady rates paired with shrinking inventory is the combination that historically ends a buyer's market rather than extends it.  November and December in Markham are not seasons of abundant choice; they are the quietest listing months of the year.  If you have seen a home this month that genuinely works for your family, the selection you are holding out for may not arrive before spring, and by spring you may be competing for it.

Our Thoughts

August was not a strong month for prices, but it was a clear month for direction: supply is contracting faster than demand, and that is what tightens a market.  If you are selling, price to recent evidence and use the thinner competition to your advantage rather than as an excuse to reach.  If you are buying, treat this fall as a narrowing window rather than a widening one.  If you want to know what this looks like on your specific street, I am happy to pull the recent sales and walk you through them - the neighbourhood picture is often quite different from the regional headline.

Bank of Canada Holds Key Rate at 2.25%

The Bank of Canada left its policy rate at 2.25 per cent this morning, which is the outcome nearly everyone expected.  But if you are buying in Markham this fall, or you have a mortgage coming up for renewal, the rate the Bank announced is not the number that will decide what your payment looks like.  The number that matters is the bond yield sitting behind fixed mortgage rates, and that one has been climbing quietly all summer while the Bank has stayed still.

What the Bank actually said

The statement itself was measured.  CPI inflation has been hovering around 3 per cent in recent months, driven mainly by persistently higher gasoline prices, while the core measures the Bank watches most closely have stayed near its 2 per cent target.  At the same time the economy came in stronger than the Bank had penciled in, with second quarter GDP up 3.3 per cent against a forecast closer to 2.5 per cent.  Set against that, new American tariffs and Canadian counter-measures were announced after trade talks between the two countries broke down, which cuts the other way entirely.  Governing Council closed by saying it will assess the sustainability of the economic rebound and the outlook for inflation, and is prepared to adjust monetary policy as needed.  That is deliberately non-committal language, and it is worth reading it as exactly that.

Why fixed rates can rise while the Bank sits still

This is the part that catches people off guard every time, so it is worth being plain about it.  Your variable rate and your line of credit are tied to prime, which sits at 4.45 per cent and does not move on a hold, so if you are carrying a variable mortgage today nothing changed for you this morning.  Fixed rates work differently.  They follow the bond market, and the Government of Canada five and ten year yields have been drifting upward since early July, with the ten year now around 3.74 per cent after a move of roughly 36 basis points.  Lenders price fixed mortgages off those yields, not off the overnight rate, which is why you can have a central bank standing perfectly still and a fixed rate quote that is meaningfully worse than the one you were given in June.

The other shift is in expectations.  For most of the past two years the conversation in this market has been about when the next cut arrives.  That conversation has changed.  Roughly 63 per cent of analysts surveyed now expect the Bank's next move to be upward rather than downward, most of them pointing to the first half of 2027, and a couple of the big banks have floated the possibility of an increase as early as October.  I am not telling you to treat that as a forecast, because these calls move around constantly and the tariff picture could turn again.  I am telling you that planning around a cut that may never come is a weaker position than it was a year ago.

What this means for Markham specifically

Our local market is tighter than the national headlines suggest.  Markham recorded 288 sales in July at an average price of $1,131,324 and a median of $1,062,500, with a sales to new listings ratio of 39.4 per cent, the tightest in York Region.  Fewer sellers came out this summer than in the past couple of years, so the well prepared, sensibly priced home is facing less resale competition heading into the fall than it did last September.  For a buyer in Unionville, Cachet, or Berczy, that means the inventory advantage you may have been counting on is thinner than you think, and waiting has a cost on both sides of the ledger now.

What I would actually do

If you are buying, get your pre-approval refreshed this week rather than next month, and hold the rate while you can, since most lenders will guarantee a quoted fixed rate for 90 to 120 days and that hold costs you nothing if rates fall.  If you are renewing in the next year, start shopping four to six months ahead instead of waiting for the letter from your lender, and get a second quote before you sign the one in front of you.  And if you are selling, price against the last ninety days of comparable sales rather than what your neighbour got in a different rate environment, because buyers in this market are doing the payment math carefully and they will notice.

The Story

The hold is not the story.  Fixed mortgage rates are being pushed up by bond yields even while the Bank sits at 2.25 per cent, and the market's expectation has quietly flipped from the next cut to the next increase.  If you are buying or renewing in Markham this fall, lock a rate hold now and plan on today's numbers rather than a cut that may not arrive.

If you want to talk through what this means for your own timing, call any time.  Over the years we have walked a lot of Markham families through decisions exactly like this one, and it is always easier with the actual numbers in front of you.

Sources: Bank of Canada policy rate announcement, September 2, 2026; Canadian Mortgage Trends, September 2026; Toronto Regional Real Estate Board July 2026 market data.

What Ontario's HST Rebate on New Homes Means for Markham Sellers This Fall

If you are planning to sell a detached home or a freehold townhouse in Markham this fall, the thing that has changed most is not the interest rate, it is who you are competing against.  Ontario's expanded HST rebate applies only to newly built homes, and over the summer it has pulled a meaningful share of buyers toward builder inventory, with single-family new home sales across the GTA finishing July up 246% over the same month a year ago.  What follows is what that shift does to your pricing and your marketing, and where an established Markham home still holds a real advantage.

The July numbers, and why they are unusual

Builders sold 1,018 new homes across the GTA in July, and 781 of those were single-family: detached, semi-detached, linked and townhomes.  That puts the single-family category roughly 50% above its ten-year July average, which is a genuinely unusual reading in a market most people still describe as slow.  At the same time, the benchmark price on those new single-family homes was $1,362,433, down 8.5% from a year ago, while new condominium apartments sold 80% below their ten-year average (source: BILD and Altus Group new home sales release for July 2026, published August 27).

I read those two facts as one story rather than two.  Builders have been discounting, the rebate stacks on top of the discount, and buyers who spent the last two years waiting have decided that the combination is finally worth acting on.  Dave Wilkes at BILD described it as the fourth consecutive month of positive momentum in the single-family category, and the pattern in the numbers supports him.

The part that catches resale sellers off guard

The rebate does not apply to a resale home.  When a buyer sits down and compares your house in Markham Village, Unionville or Cornell against a new release a few minutes up the road, they are weighing your asking price against a builder's price less a rebate that can reach well into five or six figures, and that arithmetic can look unflattering if you have anchored your expectations to what a neighbour achieved in a different market.  I would far rather you hear this from me in early September than work it out for yourself in late October, after a month of polite showings and no offers.

This is not a reason to be discouraged, and it is certainly not a reason to give the house away.  It is a reason to price and present against what is actually on the market right now instead of against memory.

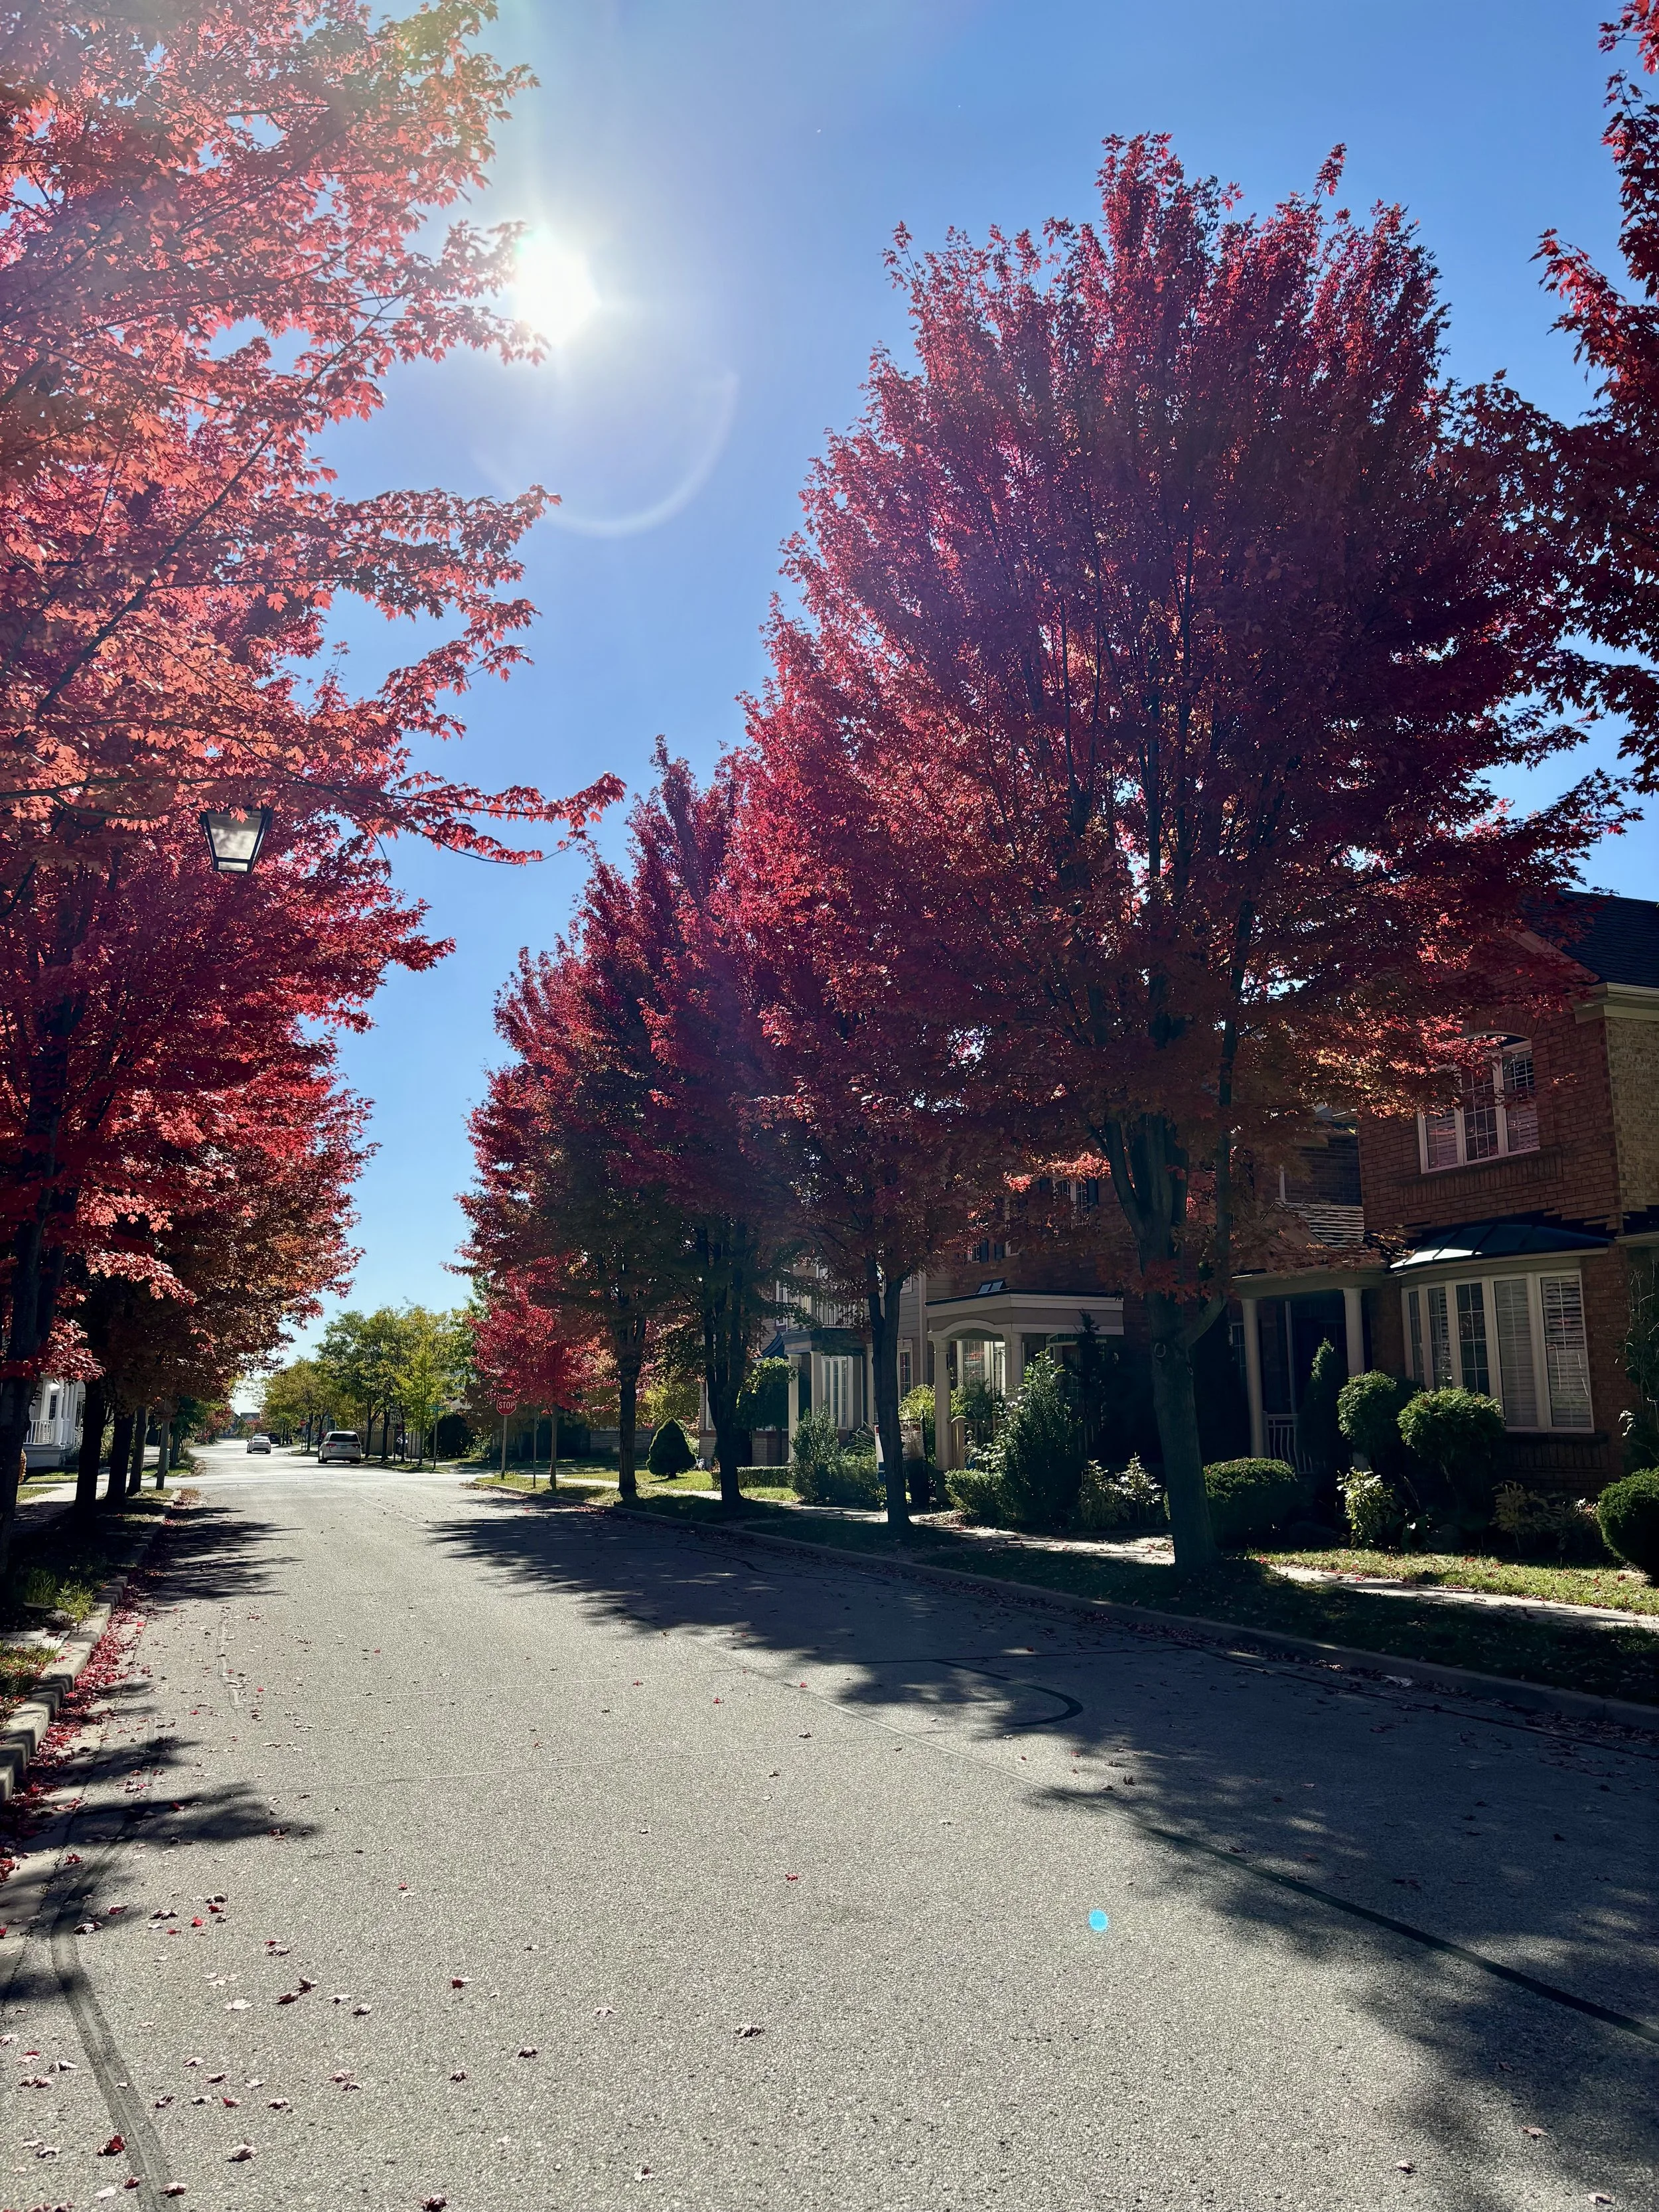
Mature Tree Lined Street in Markham

Mature Tree Lined Street in Markham

Where an established Markham home still wins

A new build is a floor plan and a rendering, and for a lot of buyers that is exactly the appeal.  But an established home in Unionville, Markham Village, Berczy, Wismer, Swan Lake or Cornell offers a set of things a builder simply cannot put in a brochure: mature trees and finished landscaping that would take fifteen years to grow in, a school assignment that is settled today rather than promised, a closing date you can actually plan a move around, and no development charge adjustments or occupancy delays waiting at the end of the process.  There is also no HST on the purchase price of a resale home, which is worth saying plainly to any buyer who has been doing the builder math and has not thought it through.

When I take a listing in one of these neighbourhoods, that is the conversation I want the marketing to be having.  Photograph the mature canopy, the established gardens, the finished basement that a new owner would otherwise spend a year and a great deal of money creating.  Sell the fifteen years the buyer does not have to wait.

How I would price into this market

Markham itself is holding up better than the headlines suggest.  There were 288 sales here in July at an average price of $1,131,324 and a median of $1,062,500, with a sales-to-new-listings ratio of 39.4%, the tightest in York Region, and roughly 4.2 months of inventory.  Across York Region as a whole, new listings were down 18.7% from a year ago (source: TRREB Market Watch, July 2026).  Fewer sellers came to market this summer, which means a well-prepared, sensibly priced home is facing less resale competition than it would have faced last fall, even with the builders active.

So the strategy is not complicated.  Price against the last ninety days of sales on streets genuinely comparable to yours, not against a builder's list price and not against 2022.  Prepare the home properly before it goes live rather than after.  And get out in front of the fall traffic, because the Bank of Canada announces its next rate decision on Wednesday, September 2, and the buyers who have been waiting on that news will be looking the following weekend.

The Buyer’s Advantage

The HST rebate has given builders an advantage on price that a resale seller cannot match dollar for dollar, so do not try to.  Compete instead on the things an established Markham neighbourhood already owns: mature setting, certainty, and a closing you can plan around, priced honestly against the last ninety days.  If you are thinking about a fall sale, I am glad to walk through your home, tell you candidly what is worth doing and what is not, and put real local numbers behind the pricing conversation.

Brad